


EUR / USD
Source: Massive (polygon.io)
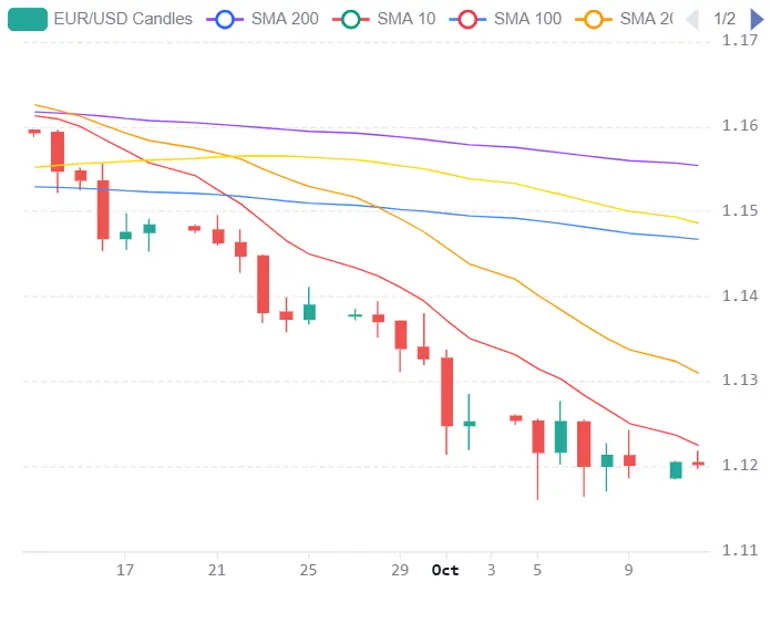
EUR/USD remains under sustained pressure around 1.1203, having recorded five consecutive weeks of losses as broad dollar strength and European fiscal concerns continue to weigh on the single currency. Safe haven demand amid escalating Middle East tensions has supported the dollar, while markets are assigning an 85% probability to another Fed rate increase by December. Attention now turns to Wednesday’s US CPI report, with headline inflation expected to accelerate towards 3.7% year on year. A stronger reading could reinforce expectations of further Fed tightening and maintain pressure on EUR/USD.
The European backdrop remains challenging, with widening French and German sovereign yield spreads reflecting growing fiscal concerns, while elevated energy costs continue to threaten growth and sustain inflation. A weaker euro further increases the cost of dollar denominated energy imports, adding to the ECB’s policy dilemma. We see these structural pressures limiting the scope for a sustained euro recovery, particularly while US yields remain elevated and geopolitical uncertainty supports demand for the dollar.
Technically, EUR/USD remains below the 20 day SMA around 1.1300, the 50 day SMA near 1.1500 and the 200 day SMA around 1.1600, confirming the broader bearish structure. The daily RSI around 24 indicates deeply oversold conditions, increasing the possibility of a corrective recovery towards 1.1300. However, we expect upside to remain constrained while the pair trades below its major moving averages. Failure to defend the early October low around 1.1166 would reinforce downside momentum and could expose the 1.1100 region, with Wednesday’s inflation report likely to determine the next directional move.
USD / JPY
Source: Massive (polygon.io)
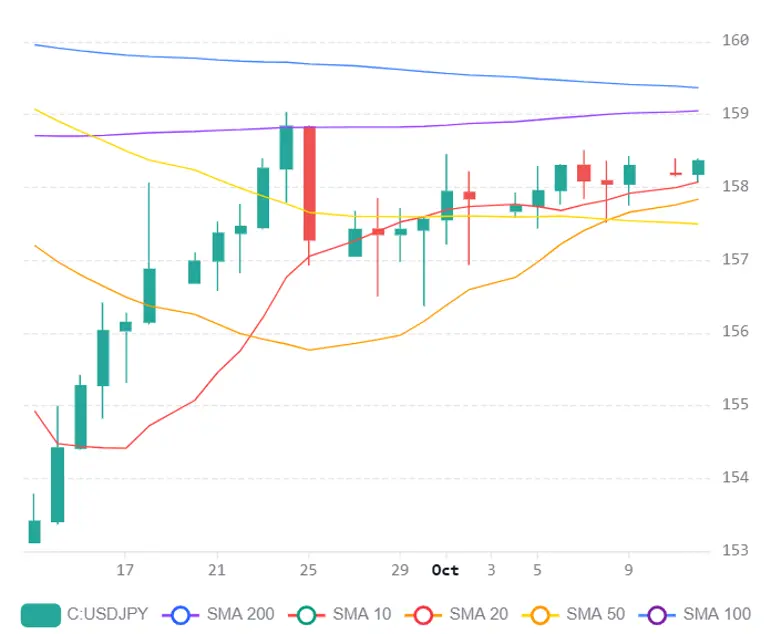
USD/JPY is consolidating around 158.40, supported by the substantial US Japan interest rate differential but facing significant resistance near the 200 day SMA around 159. Elevated US Treasury yields, with the 10 year yield above 5.2%, continue to favour the dollar, while the BoJ’s gradual tightening approach has so far been insufficient to generate sustained yen appreciation. However, expectations of another Japanese rate increase in December or January and persistent intervention concerns are limiting the pair’s upside potential.
Technically, USD/JPY remains above the 20 day SMA around 157.80 and the 50 day SMA near 157.50, maintaining a constructive near term structure. The 200 day SMA around 159 represents the immediate resistance level, with a sustained break potentially opening the way towards 160.30. We see this region as particularly important given the heightened risk of intervention around the psychologically significant 160 level. Conversely, rejection near 159 could encourage a retracement towards 157.80 and 157.50, followed by the 30 day VWAP around 156.70.
The fundamental outlook remains finely balanced. Stronger Japanese producer prices and persistent underlying inflation are reinforcing expectations of further BoJ tightening, while resilient US growth and elevated Treasury yields continue to support the dollar. We expect the US CPI release to be an important near term catalyst, with stronger inflation potentially pushing USD/JPY towards 159 to 160. However, the prospect of further Japanese policy normalisation and intervention risks should continue to constrain upside, particularly if expectations of additional Fed tightening begin to moderate.
GBP / USD
Source: Massive (polygon.io)
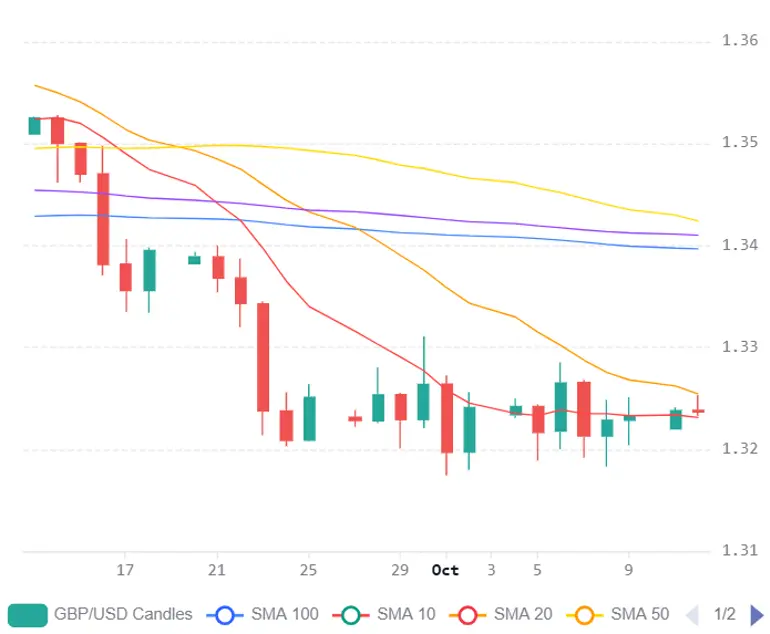
GBP/USD remains under pressure around 1.3237, trading below its major moving averages as elevated US Treasury yields and geopolitical uncertainty continue to support the dollar. The pair remains below the 20 day SMA and 30 day VWAP near 1.3300, while the 50 day and 200 day SMAs around 1.3400 provide additional resistance. Wednesday’s US CPI report represents the immediate catalyst, with headline inflation expected to accelerate towards 3.6% to 3.7%, potentially reinforcing expectations of further Fed tightening.
The UK backdrop also remains challenging, with elevated borrowing costs and growing fiscal concerns weighing on sterling. Markets continue to anticipate the possibility of further BoE tightening before year end, although higher interest rates risk placing additional pressure on domestic growth and public finances. We see the combination of fiscal uncertainty and persistent inflation as limiting sterling’s ability to benefit from expectations of higher UK rates, particularly while the dollar retains its relative yield advantage.
Technically, the daily RSI around 41 has recovered from deeply oversold territory, suggesting that downward momentum is beginning to moderate. However, GBP/USD would need to reclaim the 1.3300 region to establish a more convincing recovery, with further resistance around 1.3400. We expect the pair to remain vulnerable while trading below these levels, with a break beneath 1.3184 potentially exposing the June low near 1.3147. Conversely, softer US inflation could encourage a reassessment of Fed tightening expectations and provide scope for a corrective sterling recovery towards 1.3300.

