


EUR / USD
Source: Massive (polygon.io)
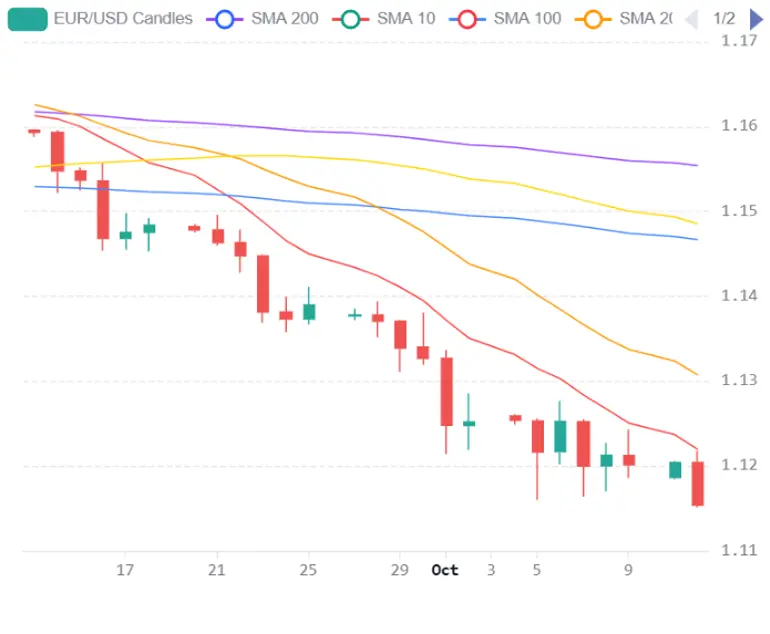
EUR/USD remains under significant selling pressure around 1.1151, extending its decline for a fifth consecutive week as elevated US yields, geopolitical uncertainty and widening policy divergence continue to favour the dollar. The Dollar Index remains near 18 month highs, supported by safe haven demand and expectations of further Fed tightening. Markets now assign around an 87% probability to another rate increase by December, while hawkish commentary from Fed officials has reinforced expectations that monetary policy may need to become more restrictive. Wednesday’s US CPI report represents the immediate catalyst, with stronger inflation potentially extending the dollar’s recent gains.
The European backdrop remains challenging, with widening French and German sovereign yield spreads reflecting growing concerns over fiscal sustainability. The spread has reached approximately 137 to 140 basis points, while speculative positioning has become increasingly favourable towards the dollar. We see these pressures limiting the euro’s ability to recover sustainably, particularly while the ECB faces a more difficult balance between persistent inflation and weaker economic growth.
Technically, EUR/USD remains well below the 20 day SMA around 1.1300, the 50 day SMA near 1.1500 and the 200 day SMA around 1.1600, confirming the broader bearish structure. The daily RSI near 20 indicates extremely oversold conditions, increasing the possibility of a corrective recovery towards 1.1300. However, we expect upside to remain constrained while the pair trades below its major moving averages. Failure to stabilise around 1.1150 would increase the likelihood of a further decline towards 1.1100, particularly if US inflation reinforces expectations of additional Fed tightening.
USD / JPY
Source: Massive (polygon.io)
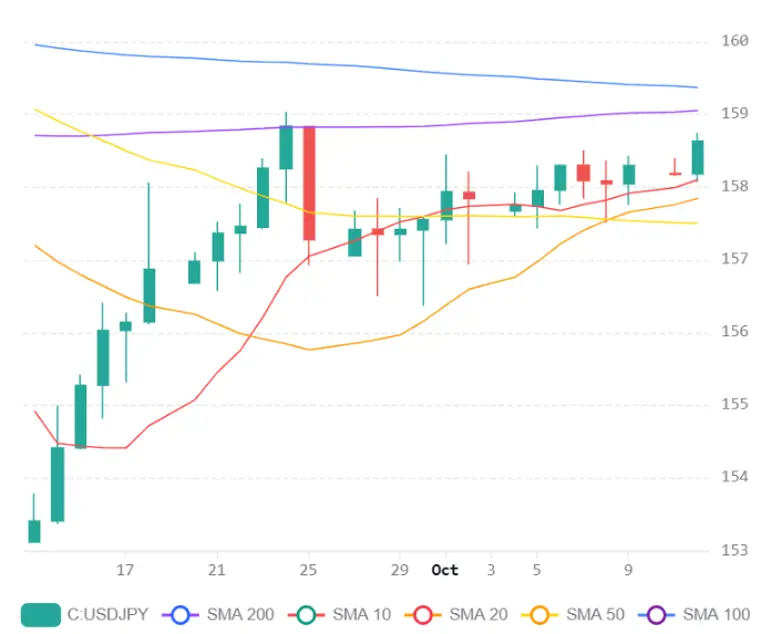
USD/JPY is trading around 158.64 as elevated US Treasury yields and a substantial interest rate differential continue to support the dollar. The Fed’s September tightening and expectations of another increase in December contrast with the BoJ’s more gradual approach, with its policy rate at 1.25%. The US 10 year Treasury yield around 5.24% continues to favour dollar denominated assets, while persistent weakness in Japanese household spending adds to the challenges facing the yen.
Technically, USD/JPY remains above the 20 day and 50 day SMAs, maintaining a constructive near term structure, although the 200 day SMA around 159 continues to provide significant resistance. The daily RSI around 60 indicates strengthening upward momentum without reaching overbought territory. We see a sustained break above 159 as an important confirmation of further upside potential, potentially opening the way towards the psychologically significant 160 level.
However, intervention concerns remain an important constraint on further yen weakness, particularly as USD/JPY approaches 160. We expect Wednesday’s US CPI report to determine whether the current recovery can extend, with stronger inflation likely to reinforce Fed tightening expectations and support a break through resistance. Conversely, a softer reading could encourage a retracement towards the 20 day SMA near 158. Reduced liquidity early in the week may also amplify price movements, leaving the pair vulnerable to abrupt reversals around these key technical levels.
GBP / USD
Source: Massive (polygon.io)
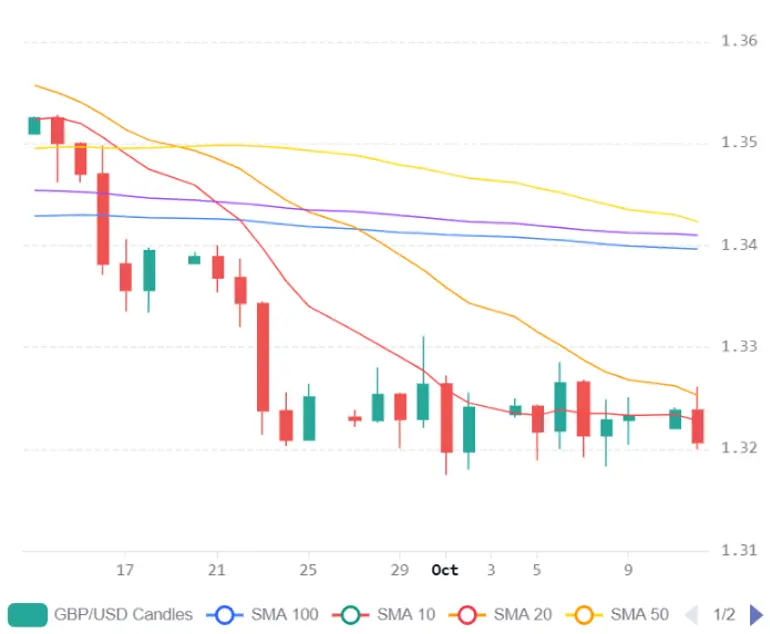
GBP/USD remains under pressure around 1.3206 as elevated US yields, hawkish Fed expectations and geopolitical uncertainty continue to support the dollar. Brent crude above USD 106 per barrel is adding to global inflation concerns, while markets now assign around an 87% probability to another Fed increase by December. Wednesday’s US CPI report, with headline inflation expected to accelerate towards 3.6%, represents the principal near term catalyst for determining whether the recent dollar strength can persist.
The UK policy outlook provides some potential support for sterling, with markets assigning around a 90% probability to a BoE rate increase in November. However, uncertainty ahead of the UK budget and concerns over the domestic growth outlook continue to limit the currency’s appeal. We see Governor Bailey’s upcoming remarks as an important opportunity for markets to reassess the BoE’s policy trajectory, although the relative strength of US yields and persistent geopolitical risks remain significant headwinds.
Technically, GBP/USD remains below the 20 day SMA around 1.3300 and the 50 day and 200 day SMAs clustered near 1.3400, maintaining the broader bearish structure. The daily RSI around 38 indicates persistent downward momentum without reaching oversold territory. We see 1.3184 as the immediate support level, with a decisive break potentially exposing the June low around 1.3147. Conversely, a recovery from this area could provide scope for a corrective move towards 1.3300, although we expect upside to remain limited unless softer US inflation prompts a meaningful reassessment of Fed tightening expectations.

