


EUR / USD
Source: Massive (polygon.io)
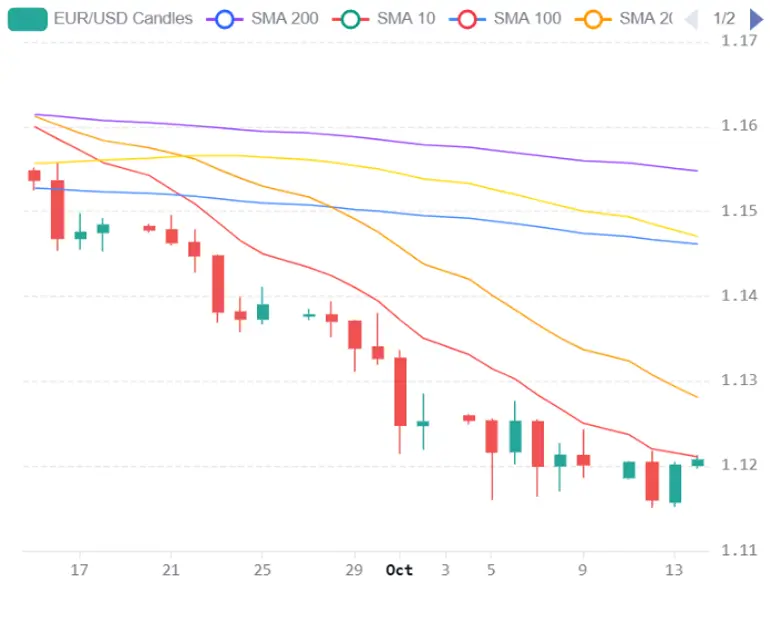
EUR/USD has recovered modestly to around 1.1206 from its recent low near 1.1154, although the broader downward trend remains intact following a decline of approximately 3% over the past month. The Fed’s policy rate of 3.75% to 4.00% continues to provide a substantial yield advantage for the dollar, while elevated energy prices and geopolitical uncertainty sustain demand for safe haven assets. Attention now turns to today’s US CPI report, with headline inflation expected to accelerate to 3.6% year on year. A stronger reading, particularly in core inflation, could reinforce expectations of further Fed tightening and renew pressure on the euro.
The European backdrop remains challenging, with France’s fiscal difficulties and subdued eurozone growth adding to the currency’s vulnerability. Elevated French sovereign yields, public debt approaching 120% of GDP and ongoing political uncertainty continue to weigh on investor confidence. We see these structural pressures limiting the scope for a sustained euro recovery, particularly while Brent crude above USD 106 per barrel threatens growth across the energy dependent eurozone.
Technically, EUR/USD remains below the 20 day SMA around 1.1300, the 30 day VWAP near 1.1400 and the 50 day and 200 day SMAs clustered around 1.1500. The daily RSI has recovered towards 31, suggesting that selling pressure is beginning to moderate after deeply oversold conditions. We see scope for a corrective recovery towards 1.1300 if the pair can stabilise above 1.1210, although the broader technical structure remains bearish. Conversely, renewed weakness below this level would expose the recent low around 1.1154, with a sustained break potentially opening the way towards 1.1100.
USD / JPY
Source: Massive (polygon.io)
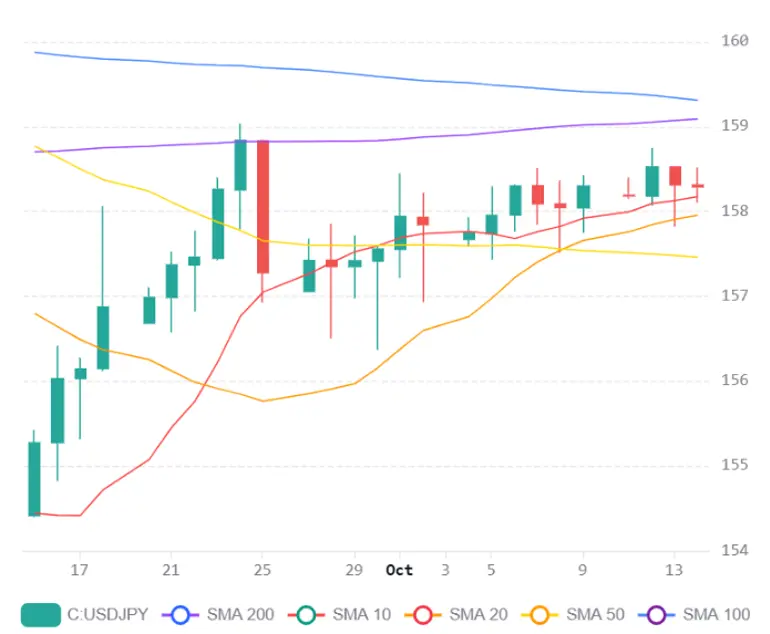
USD/JPY is consolidating around 158.29 as the pair remains caught between a substantial US Japan interest rate differential and growing uncertainty over the Fed’s next policy move. Elevated US Treasury yields, with the 10 year yield around 5.19%, continue to support the dollar, although recent comments from Fed officials suggesting that higher long term borrowing costs are already tightening financial conditions have moderated expectations of further rate increases. Meanwhile, the BoJ is widely expected to leave rates unchanged in October, with markets assigning only a 6% probability to another increase, although the possibility of tightening in December continues to provide some support for the yen.
Technically, USD/JPY remains above the 20 day SMA around 158.00 but below the 200 day SMA near 159.00, leaving the pair confined within a relatively narrow trading range. The recent recovery from 157.84 suggests underlying buying interest remains intact, although repeated difficulty overcoming the 200 day SMA continues to limit upside momentum. We see a sustained break above 159.00 as necessary to establish a more convincing recovery towards the psychologically important 160.00 resistance level.
We expect today’s US CPI report to be the immediate catalyst for a potential break from the current range. Stronger inflation could reinforce Fed tightening expectations and support a move towards 159.00 to 160.00, while a softer reading would strengthen the case for a prolonged Fed pause and could push USD/JPY below the 20 day SMA towards the 50 day SMA around 157.50. Elevated energy costs remain an additional headwind for Japan, although expectations of further BoJ policy normalisation and intervention concerns should continue to limit the extent of yen weakness.
GBP / USD
Source: Massive (polygon.io)
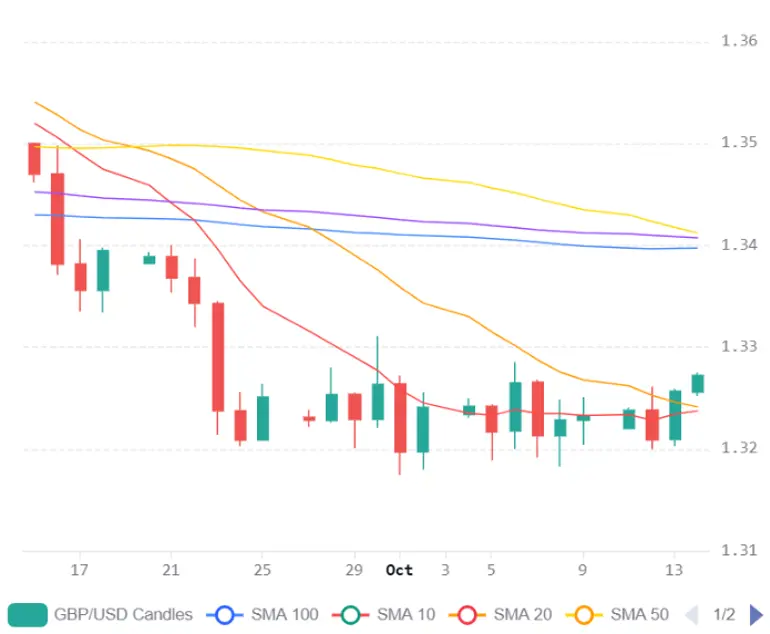
GBP/USD has recovered approximately 0.36% to around 1.3272, supported by improving momentum and a more balanced outlook for relative monetary policy expectations. Markets now assign around a 77% probability to the Fed leaving rates unchanged at its next meeting, compared with 51% a month ago, while persistent UK inflation continues to support expectations of a restrictive BoE policy stance. This shift has provided sterling with some relief from the dollar strength that dominated recent sessions.
The UK policy outlook remains comparatively supportive, with BoE officials suggesting that Bank Rate at 3.75% may not be sufficiently restrictive to contain persistent inflation. However, elevated energy prices and geopolitical uncertainty continue to present risks for the UK economy. We see these competing forces keeping sterling sensitive to changes in US rate expectations, particularly ahead of today’s CPI release. Stronger US inflation could revive dollar demand, while softer core inflation would reinforce expectations of a Fed pause and provide further support for GBP/USD.
Technically, the pair has recovered above the 20 day SMA around 1.3200 but remains below the 30 day VWAP near 1.3300 and the 50 day and 200 day SMAs around 1.3400. The daily RSI has risen towards 47 from previously oversold levels, indicating improving momentum without yet confirming a sustained upward trend. We expect a break above 1.3300 to strengthen the recovery and potentially expose 1.3330, while failure to clear this resistance could encourage renewed selling towards the 20 day SMA around 1.3200.

