EUR / USD
Source: Massive (polygon.io)
EURUSD
The EUR/USD pair faces a challenging fundamental and technical backdrop, with French fiscal turmoil and sustained Federal Reserve hawkishness converging to pressure the single currency. France's 10-year bond yield has approached 5% — its highest since 2002 — while the OAT-Bund spread has widened to approximately 153 basis points, and an imminent Moody's rating review with expectations of a downgrade to single-A is compounding the sovereign risk premium embedded in European assets. The ECB's position is further complicated by France's ineligibility for bond market stabilisation tools under the excessive deficit procedure, leaving it with limited means to address widening spreads even as German producer prices accelerated sharply to 6.7% year-on-year, underscoring persistent inflationary pressures that preclude a dovish pivot.
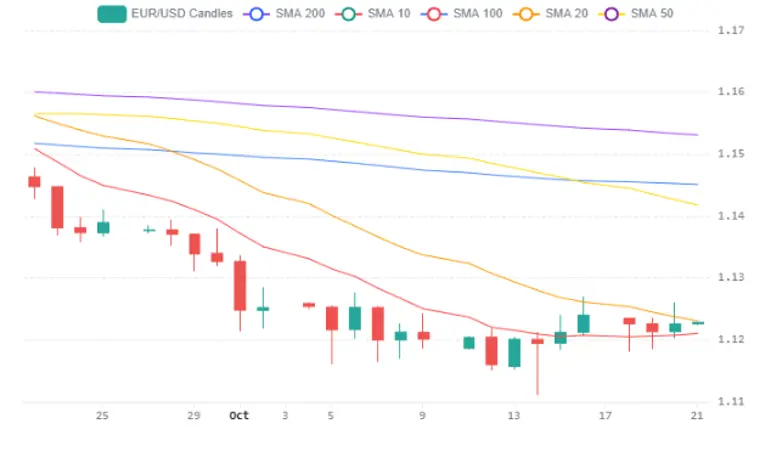
On the U.S. side, oil-driven inflation fears and a 94% market-implied probability of a December Fed hike sustain the dollar's yield advantage, while the eurozone current account surplus has narrowed sharply to 7.7 billion euros from 18.1 billion a year earlier, eroding a traditional pillar of euro strength. The technical picture reflects this bearish macro tilt: the pair sits well below the 200-day moving average at 1.15, the 50-day SMA at 1.14, having shed roughly 3.5% over the past month. While the bounce off last week's low near 1.1116 has been constructive and the daily RSI has recovered from depressed levels, the failure to sustain gains above the 1.1260 resistance zone suggests sellers remain firmly active at higher levels.
A bullish scenario would require consolidation above the 20-day SMA at 1.12 and an eventual challenge of the 1.13 VWAP, but this appears unlikely without a meaningful de-escalation in French political risks or a dovish shift in Fed rhetoric. Until those catalysts materialize, the balance of risks favours renewed selling pressure toward the 1.1116 support, with the macro fundamentals continuing to support a cautious-to-bearish outlook for EUR/USD.
USD / JPY
Source: Massive (polygon.io)
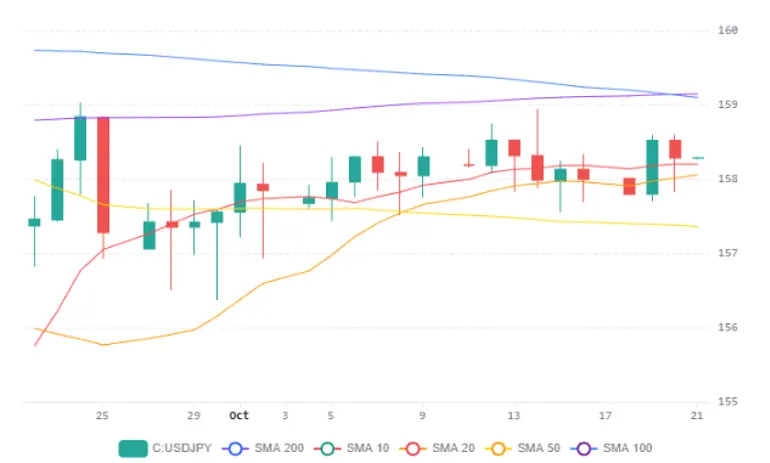
USD/JPY is currently navigating a tug-of-war between a narrowing but still wide Japan-U.S. interest rate differential and growing expectations of accelerated Bank of Japan tightening. The pair closed near 158.29 after a modest 0.16% decline, trading below the critical 200-day moving average at approximately 159, which now serves as significant overhead resistance. A strong consensus among economists points to the BOJ raising its policy rate to 1.50% at its December meeting, an acceleration that, if realized, would provide structural support for the yen and add downward pressure on the pair.
From a technical standpoint, the daily RSI near 55 reflects neutral momentum, while the price action—where dip buyers stepped in near the 20-day moving average around 158—suggests the market is not yet ready to commit to a directional break. The 30-day rolling VWAP at approximately 157.84 has risen notably, reflecting the broader uptrend from September's lows near 153, but a decisive move above the 200-day SMA at 159 is needed to target the psychologically important 160 resistance cluster.
On the macro front, political friction in Japan—highlighted by dissenting board votes against the September rate hike and Prime Minister Takaichi's expansionary fiscal stance—introduces uncertainty about the pace of BOJ tightening, which could delay yen appreciation if the central bank pushes its next move into the new year. The interplay between BOJ hawkishness, softening U.S. Treasury yields, and strong demand for Japanese government bonds will likely determine whether USD/JPY breaks above 159 or retreats toward the 50-day moving average near 157.36 in the weeks ahead.
GBP / USD
Source: Massive (polygon.io)
The GBP/USD pair is being propelled higher by a clear divergence in monetary policy expectations, with UK unemployment falling unexpectedly to 4.7% and wage growth accelerating to 3.7%, pushing the probability of a 25-basis-point BOE hike at the November meeting to roughly 96%. In contrast, the Federal Reserve is widely expected to hold rates steady at its upcoming meeting, with weak US housing data—including pending home sales at a 25-year low—further softening dollar sentiment by underscoring the strain of elevated borrowing costs on the American economy.
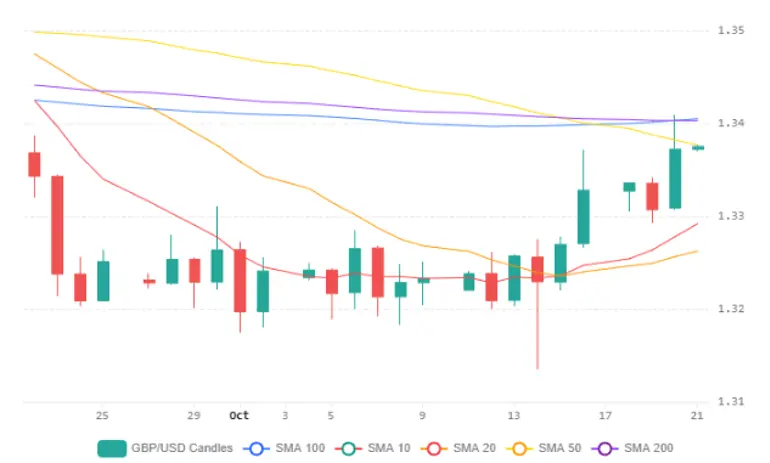
From a technical perspective, the pair rallied 0.44% through the session to an intraday high near 1.3408, where it encountered meaningful resistance at the converging 200-day and 50-day simple moving averages around 1.34. Daily RSI surged to approximately 58.5, a sharp departure from the sub-40 readings that dominated the prior month's sell-off, signalling a notable momentum shift after the bounce off 1.3150 support. A decisive break above the 1.34 confluence could open a path toward the 1.3607 resistance zone, while failure at that level risks a retreat below the 30-day VWAP at 1.33 and a retest of the October lows.
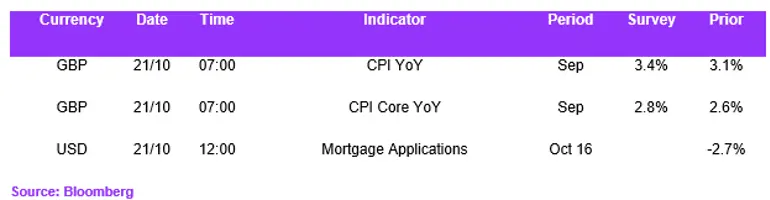
Sterling is also drawing indirect support from euro weakness tied to fiscal and political turmoil in France, as capital flows favour the UK's relative stability, and Wednesday's UK CPI release—expected to show headline inflation accelerating to around 3.4%—represents the next critical catalyst that could cement BOE tightening expectations and provide additional lift to the pair.
Economic Calendar