EUR / USD
Source: Massive (polygon.io)
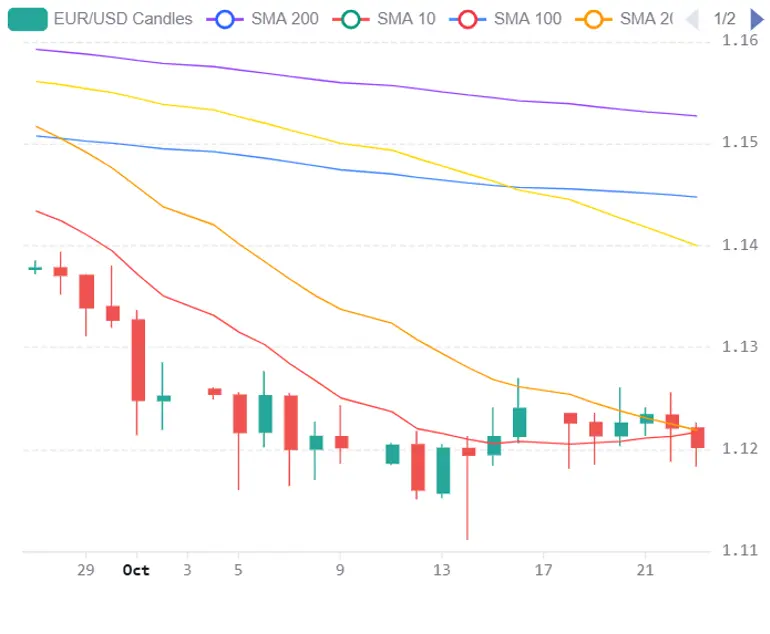
EUR/USD remains under pressure around 1.1200 as markets await closely spaced Fed and ECB policy decisions. Both central banks are expected to leave rates unchanged, with the Fed maintaining its target range at 3.75% to 4.00% and the ECB holding its deposit rate at 2.50%. However, the divergence in economic performance continues to favour the dollar, with US growth expectations considerably stronger than those for the eurozone. Elevated US Treasury yields, with the 10 year yield near 5%, provide additional support for dollar denominated assets, while Brent crude above $116/bbl threatens growth across the energy dependent eurozone.
The fundamental outlook remains challenging for the euro, although expectations of further Fed tightening may already be largely reflected in market pricing. This could limit additional dollar upside if policymakers adopt a more cautious tone. We see the upcoming central bank communications as particularly important in determining whether the current rate differential can continue to support the dollar, with any dovish shift in Fed guidance potentially providing scope for a corrective euro recovery.
Technically, EUR/USD remains below the 50 day SMA around 1.1400 and the 200 day SMA near 1.1500, maintaining the broader bearish structure. The daily RSI has recovered towards 36 from deeply oversold territory, suggesting that selling pressure is beginning to moderate. We see 1.1190 as the immediate support level, with a sustained break potentially exposing the October low near 1.1116. Conversely, a recovery above the 20 day SMA around 1.1200 would shift attention towards 1.1280 and the 30 day VWAP near 1.1300. However, we expect upside to remain constrained while the broader growth and yield differentials continue to favour the dollar.
USD / JPY
Source: Massive (polygon.io)
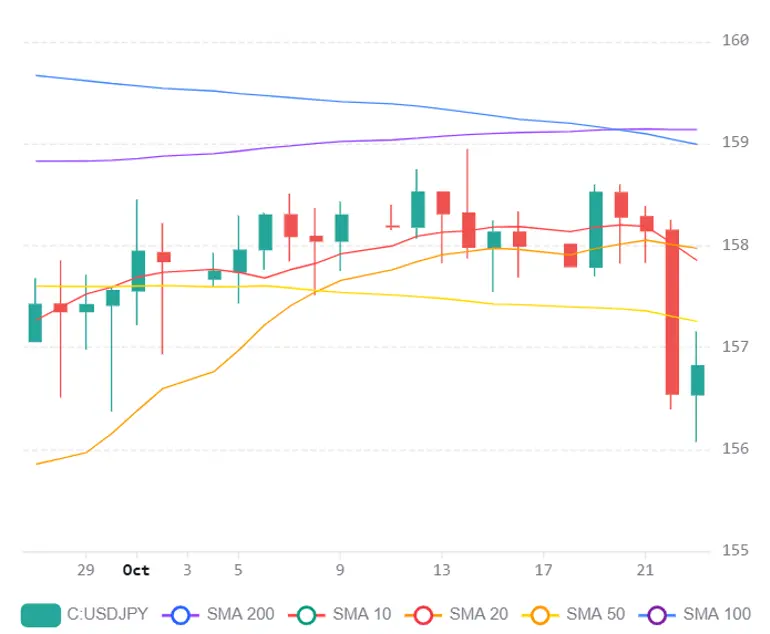
USD/JPY is trading around 157.00 as markets prepare for the upcoming Fed and BoJ policy decisions. The Fed is expected to leave rates unchanged at 3.75% to 4.00%, while the BoJ is likely to maintain its policy rate at 1.25%. Although the substantial US Japan rate differential continues to support the dollar, recent declines in US Treasury yields and expectations of further Japanese policy normalisation have weighed on USD/JPY. We see the accompanying central bank guidance as more important than the decisions themselves, particularly regarding the likelihood of a December Fed increase and the timing of further BoJ tightening.
The fundamental backdrop remains finely balanced. A hawkish Fed could reinforce the dollar’s yield advantage and encourage a recovery, while stronger BoJ inflation projections could support expectations of further tightening and strengthen the yen. Brent crude near $117/bbl adds uncertainty by increasing Japan’s import costs while also sustaining global inflation concerns and encouraging safe haven demand during periods of market stress. We expect these competing forces to maintain volatility, particularly as markets assess incoming US growth and inflation data alongside both central banks’ policy guidance.
Technically, USD/JPY remains below the 20 day SMA around 158.00, the 50 day SMA near 157.30 and the 200 day SMA around 159.00, confirming a weaker near term structure. The daily RSI around 41 indicates subdued momentum following the recent reversal from 158.60. We see 156.70 as the immediate support level, with a sustained break below 156.00 potentially exposing the September lows around 153.00. Conversely, a recovery above 157.30 would improve the technical picture and shift attention towards 158.00, followed by the more significant resistance around 159.00.
GBP / USD
Source: Massive (polygon.io)
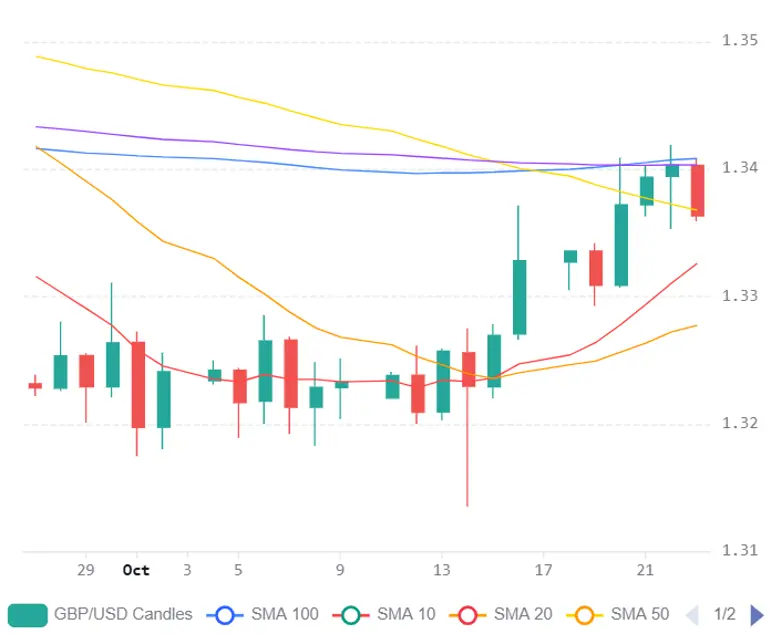
GBP/USD has retreated to around 1.3363 after failing to sustain its recent recovery towards 1.3400, as weakening UK consumer confidence and uncertainty ahead of the Autumn Budget weigh on sterling. The GfK consumer confidence index fell sharply to minus 24, highlighting growing concerns over household finances and economic prospects. Meanwhile, elevated US yields and expectations of further Fed tightening continue to support the dollar, with markets assigning around a 68% probability to another rate increase in December.
The UK monetary policy outlook remains uncertain, with market expectations of further BoE tightening appearing more aggressive than economists’ forecasts. While persistent inflation continues to support the case for higher rates, weaker domestic demand and potential tax increases could limit the scope for additional tightening. Brent crude around $116/bbl presents another challenge by sustaining inflationary pressures while weighing on household spending and growth. We see these developments as limiting sterling’s recovery potential, particularly if upcoming US data reinforce expectations of a more restrictive Fed policy stance.
Technically, GBP/USD remains above the 20 day SMA and 30 day VWAP around 1.3300 but continues to face resistance from the 50 day and 200 day SMAs clustered near 1.3400. The daily RSI around 56 indicates that momentum remains moderately positive, although the recent retreat suggests the recovery is losing strength. We see 1.3300 as the critical support required to preserve the recent improvement, with a sustained break potentially exposing the October low around 1.3150. Conversely, a decisive move above 1.3400 would strengthen the bullish structure and open the way towards 1.3600. For now, we expect UK fiscal uncertainty and the relative Fed policy outlook to keep the balance of risks tilted modestly to the downside.
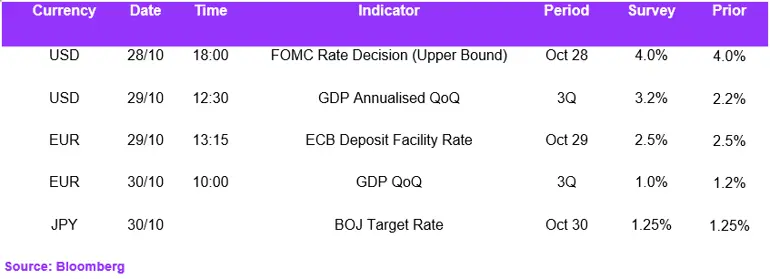
Economic Calendar