


EUR / USD
Source: Massive (polygon.io)
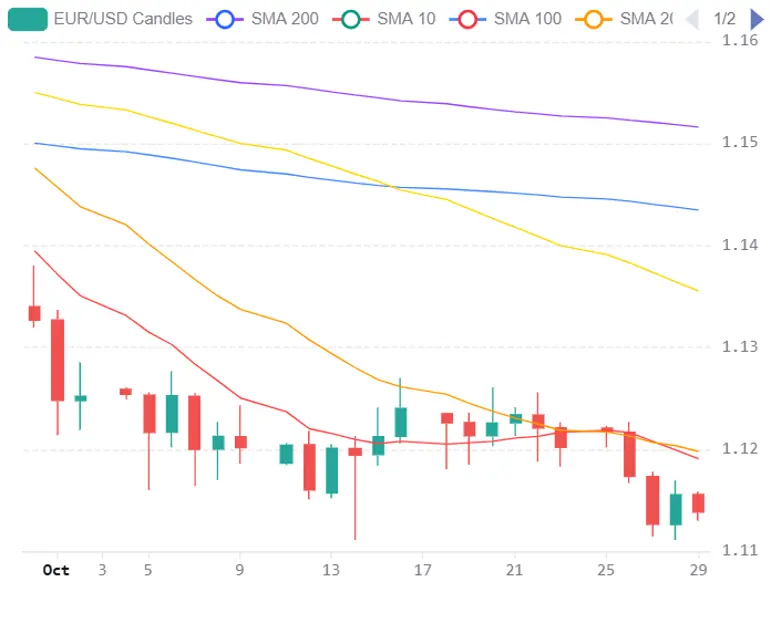
EUR/USD remains under sustained pressure around 1.1138, trading near its lowest levels in more than a year as elevated US yields and persistent European economic challenges continue to favour the dollar. The Fed has maintained its policy rate at 3.75% to 4.00%, with two officials favouring an immediate increase, while markets continue to assign around a 78% probability to further tightening in December. Meanwhile, the ECB is expected to leave its deposit rate unchanged at 2.50%, with elevated energy costs and growing fiscal concerns limiting the eurozone’s economic outlook. Brent crude above USD 114 per barrel adds to these pressures, increasing the risk of persistent inflation alongside weaker growth.
Market positioning also reflects the euro’s vulnerability, with speculative net short positions reportedly reaching approximately USD 18.9 billion. French fiscal concerns and elevated sovereign yields have further weakened sentiment towards the single currency. We see the combination of widening policy divergence, European fiscal uncertainty and elevated energy costs as maintaining a challenging fundamental backdrop, although increasingly stretched positioning could amplify any recovery if US economic data disappoint expectations.
Technically, EUR/USD remains below the 20 day SMA and 30 day VWAP around 1.1200, the 50 day SMA near 1.1400 and the 200 day SMA around 1.1500, confirming the broader bearish structure. The daily RSI around 33 indicates oversold conditions, increasing the possibility of a corrective recovery. We expect today’s US GDP and PCE inflation releases, alongside ECB President Lagarde’s guidance, to determine the next directional move. Stronger US data could reinforce Fed tightening expectations and expose 1.1050 to 1.1000, while softer readings could encourage short covering towards 1.1200. However, upside is likely to remain constrained while the pair trades below its major moving averages.
USD / JPY
Source: Massive (polygon.io)
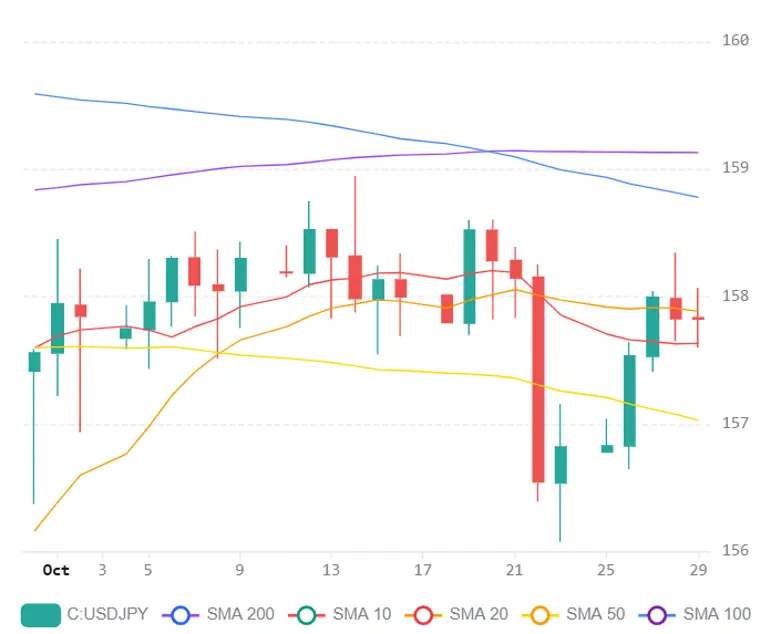
USD/JPY is consolidating around 157.80 as markets assess the Fed’s latest policy decision ahead of Friday’s BoJ meeting. The Fed maintained rates at 3.75% to 4.00%, although its cautious guidance on further tightening has tempered the dollar’s recent momentum. Markets continue to price a substantial probability of another increase in December, while persistent US inflation provides underlying support for Treasury yields. However, expectations of further Japanese monetary policy normalisation are increasingly challenging the dollar’s interest rate advantage.
The BoJ is widely expected to maintain its policy rate at 1.25%, with attention focused on its assessment of underlying inflation and the prospects for additional tightening in December. Stronger Japanese inflation indicators have reinforced expectations that price pressures are becoming more firmly established, potentially providing the central bank with greater confidence to continue raising rates. We see a more hawkish BoJ outlook as supportive of the yen, particularly alongside persistent intervention concerns, although the substantial US Japan rate differential continues to limit the scope for sustained appreciation.
Technically, USD/JPY remains confined between the 50 day SMA around 157.00 and the 200 day SMA near 159.00, while the daily RSI around 51 reflects broadly neutral momentum. We see 159.00 as the critical resistance level, with a sustained break potentially opening the way towards the psychologically important 160.00 region. Conversely, a move below the 50 day SMA would weaken the near term structure and increase the likelihood of further downside. We expect Friday’s BoJ communication to be the principal catalyst, with a stronger commitment to further tightening potentially encouraging a more sustained yen recovery.
GBP / USD
Source: Massive (polygon.io)
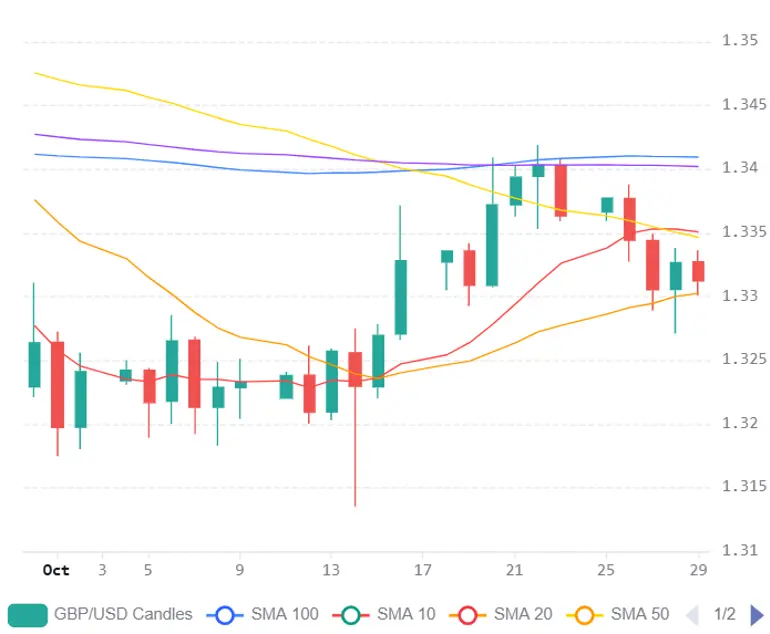
GBP/USD has recovered modestly to around 1.3312 after testing an intraday low near 1.3273, although the broader outlook remains constrained by UK fiscal uncertainty and relatively hawkish Fed expectations. The Fed’s decision to maintain rates at 3.75% to 4.00% has preserved the dollar’s yield advantage, with markets assigning around a 78% probability to another increase in December. Meanwhile, persistent UK inflation around 3.5% continues to complicate the BoE’s policy outlook ahead of its November meeting, with policymakers divided over the need for further tightening.
The domestic backdrop remains challenging following the UK Budget, with fiscal headroom estimated around GBP 15 billion and projected borrowing increases raising concerns over the sustainability of public finances. These pressures could limit sterling’s ability to benefit from expectations of higher UK interest rates, particularly if tighter financial conditions weigh on economic growth. We see the combination of fiscal uncertainty and persistent inflation as maintaining a cautious outlook for the pound, although softer US data could provide some temporary relief.
Technically, GBP/USD remains above the 20 day SMA around 1.3300 but below the 50 day and 200 day SMAs clustered between 1.3350 and 1.3400. We see 1.3300 as the immediate support required to preserve the recent recovery, while a sustained move above 1.3360 would strengthen the technical picture and expose 1.3400. Conversely, failure to defend 1.3300 could encourage renewed selling towards the mid October low around 1.3150. We expect today’s US GDP and PCE inflation data to provide the immediate catalyst, with stronger readings potentially reinforcing dollar strength while softer figures could support a recovery towards the upper end of the current trading range.

