


EUR / USD
Source: Massive (polygon.io)
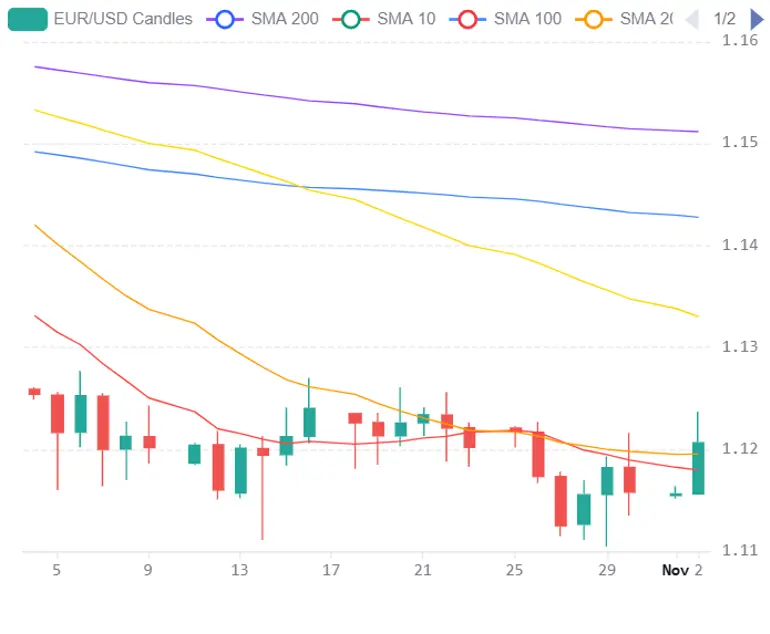
EUR/USD has recovered towards the critical 1.1200 level, although the broader outlook remains constrained by dollar strength and persistent eurozone economic and fiscal concerns. Robust US GDP growth of 3.4% and expectations of further Fed tightening continue to favour the dollar, while uneven eurozone growth and renewed fiscal uncertainty in France weigh on the single currency. Nevertheless, extreme speculative euro short positioning increases the risk of a sharper recovery should US economic data disappoint or dollar sentiment weaken.
Technically, the pair has rebounded from its annual low of 1.1115, with the daily RSI recovering to around 46, suggesting improving momentum. However, resistance around 1.1220 to 1.1240 continues to limit gains, while the 50 DMA near 1.1300 remains a more significant obstacle. We expect the 1.1200 area to remain pivotal, with a sustained break above 1.1240 potentially encouraging further upside towards 1.1300. Conversely, renewed weakness below 1.1200 could expose the recent lows. Upcoming US employment figures, eurozone inflation data and the US midterm elections are likely to determine near term direction, with lower oil prices providing some relief to the energy importing eurozone.
USD / JPY
Source: Massive (polygon.io)
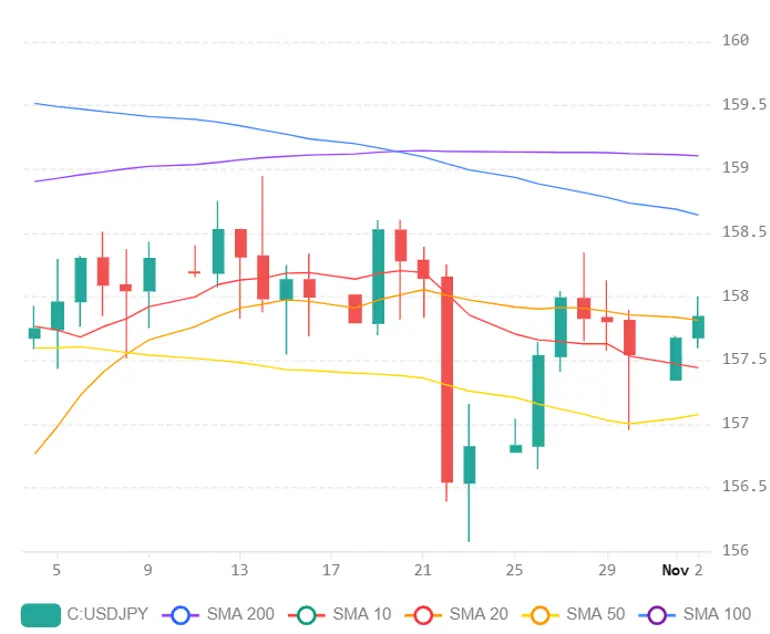
USD/JPY remains caught between the substantial US and Japanese interest rate differential and growing expectations of further Bank of Japan tightening. The BoJ's increasingly confident inflation assessment has strengthened expectations of a December rate increase, supporting the case for gradual yen appreciation. However, resilient US economic activity and continued expectations of Fed tightening are likely to preserve some support for the dollar, limiting the scope for a sustained decline in the pair.
Technically, USD/JPY trades near 157.91, holding above its 20 DMA around 157.81 and 50 DMA near 157.07, while the 200 DMA at approximately 159.12 remains a key resistance level. The daily RSI around 52 suggests limited directional conviction, with the pair struggling to establish momentum above 158. We see a sustained break above 159 opening the way towards 160, while a move below the 157.80 support area could prompt a retreat towards 156.43. Falling oil prices and some unwinding of carry trades may provide additional support for the yen, although upcoming US employment figures and central bank signals will remain the principal drivers. Overall, we maintain a cautiously bearish medium term outlook for USD/JPY as expectations of further BoJ tightening strengthen.
GBP / USD
Source: Massive (polygon.io)
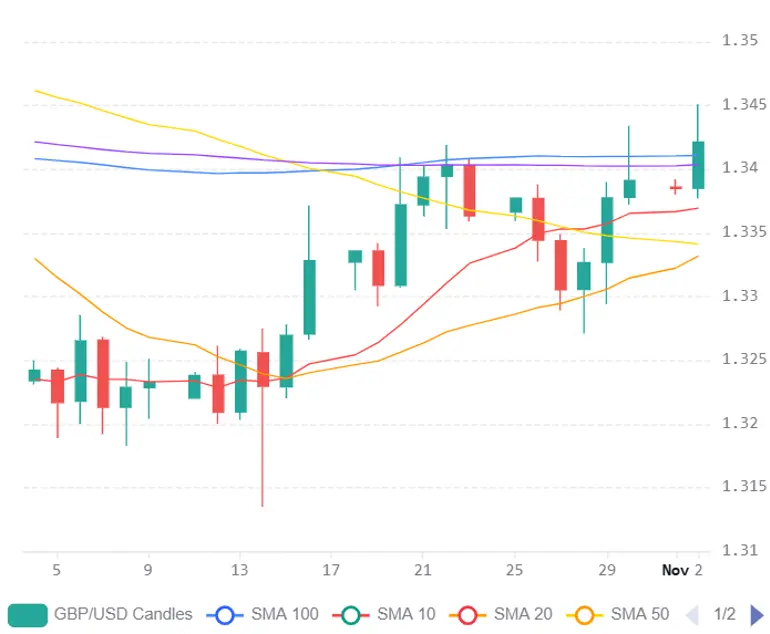
GBP/USD has extended its recent recovery towards 1.3421, supported by improving technical momentum and expectations of further Bank of England tightening. The pair has reclaimed its 200 DMA near 1.3400 and remains above its shorter term moving averages, while the daily RSI around 60.5 points to strengthening buying interest. However, repeated resistance near 1.3428 suggests that further gains may require a stronger catalyst.
Attention now turns to Thursday's BoE decision, with a 25 basis point rate increase to 4.00% largely priced in. The MPC's voting split and forward guidance are therefore likely to prove more influential for sterling, particularly if policymakers challenge expectations of several additional increases. Improving UK business activity provides some support, although fiscal uncertainty and elevated public debt remain potential headwinds. Meanwhile, resilient US economic data continue to underpin the dollar, despite lower oil prices easing some inflation concerns. We expect a sustained break above 1.3428 to open the way towards 1.3500, with scope for further gains towards 1.3664 if dollar weakness accelerates. Conversely, disappointment from the BoE or stronger US employment figures could trigger a retreat towards 1.3340, followed by 1.3260. The near term outlook remains cautiously constructive, although US political developments and monetary policy expectations could generate considerable volatility.

