


EUR / USD
Source: Massive (polygon.io)
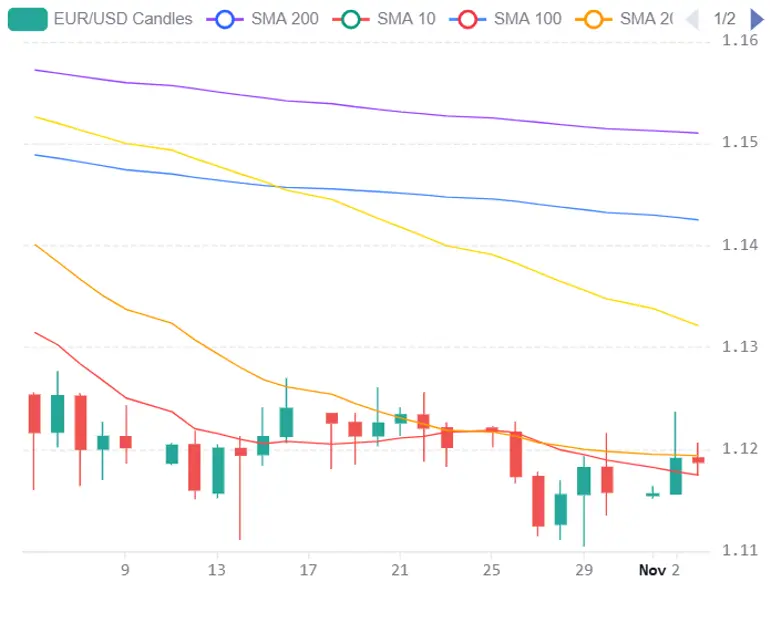
EUR/USD remains under pressure near 1.1188 as elevated US Treasury yields and renewed fiscal concerns in Europe continue to support the dollar. Despite markets pricing a higher probability of an ECB rate increase in December than an equivalent Fed move, the US retains a substantial yield advantage, with the 10 year Treasury yield approaching 4.95%. Stronger US labour market data, including a rise in JOLTS job openings to 7.52 million, have reinforced expectations of further Fed tightening. Meanwhile, improving eurozone manufacturing activity provides some support for the euro, although France's deteriorating fiscal outlook continues to weigh on sentiment.
Technically, the pair remains below its key moving averages, with the 20 DMA near 1.1200 providing immediate resistance, followed by the 50 DMA around 1.1300. The daily RSI has recovered to approximately 43, suggesting that selling pressure is easing, although the broader trend remains bearish. We expect the 1.1200 level to remain pivotal, with a sustained recovery potentially triggering short covering towards 1.1300. Conversely, a break below 1.1175 could expose the annual low near 1.1115. Upcoming eurozone inflation figures and US employment data are likely to determine near term direction, with the balance of risks remaining modestly skewed to the downside.
USD / JPY
Source: Massive (polygon.io)
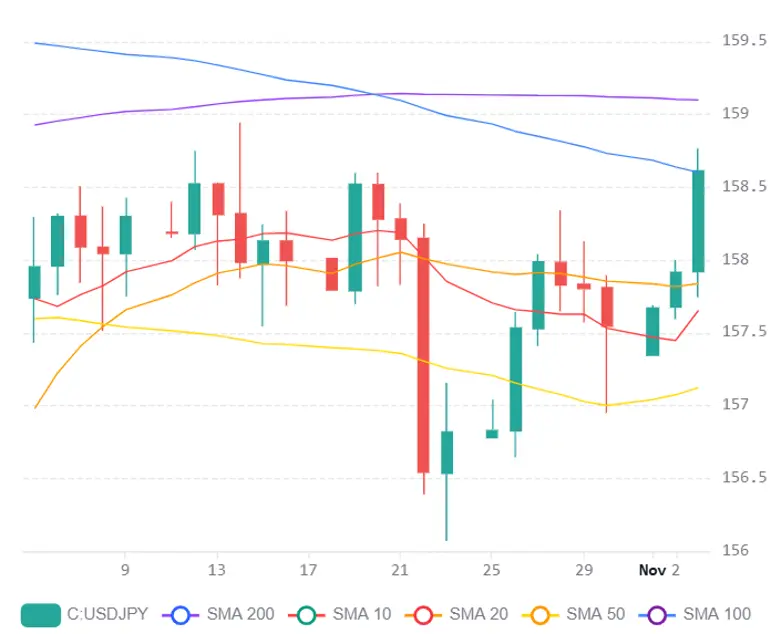
USD/JPY has strengthened towards 158.63 following stronger US economic data, which reinforced expectations of further Fed tightening and supported Treasury yields. The rise in JOLTS job openings to 7.52 million, alongside improving factory orders, has maintained the dollar's interest rate advantage over the yen. However, growing expectations of a December Bank of Japan rate increase and renewed warnings of potential currency intervention could limit further upside, particularly as the pair approaches the psychologically important 160 level.
Technically, USD/JPY has moved above its 20 DMA near 158.00 and 50 DMA around 157.00, while the daily RSI has risen towards 59, indicating improving upward momentum. Nevertheless, the 200 DMA near 159.00 remains a significant resistance level. We see a sustained break above this area opening the way towards 160.00, although intervention concerns could discourage aggressive yen selling. Conversely, rejection around 159.00 may trigger a retreat towards the 20 DMA near 158.00. With US political developments and shifting monetary policy expectations likely to influence sentiment, we expect volatility to remain elevated, while the near term bias favours further dollar strength.
GBP / USD
Source: Massive (polygon.io)
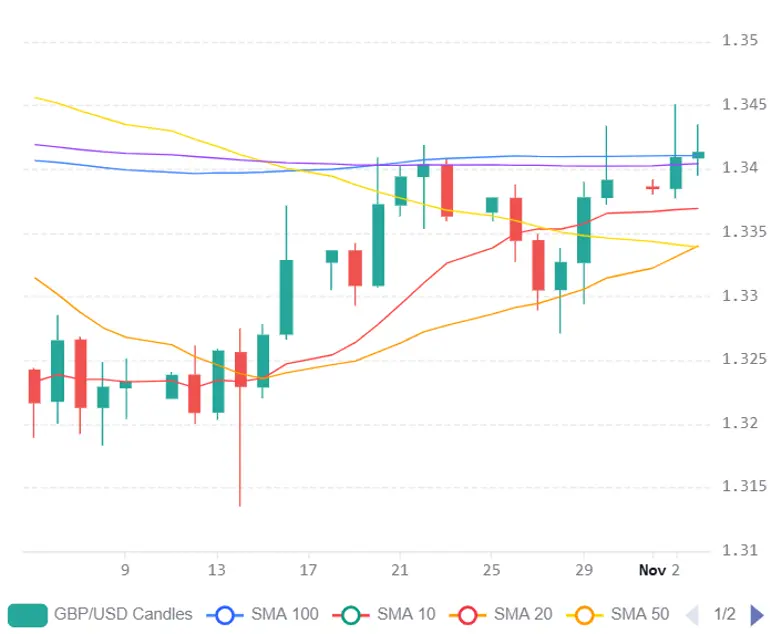
GBP/USD is consolidating near 1.3411 as expectations of further Bank of England tightening continue to support sterling. Persistent UK inflation, particularly in services, has reinforced expectations of a 25 basis point rate increase to 4.00% this week, while UK gilt yields remain above their US counterparts. However, stronger US labour market data and elevated Treasury yields continue to underpin the dollar, potentially limiting sterling's upside. Lower energy prices have provided additional support for the pound, although market expectations for further BoE tightening may prove excessive if policymakers adopt a more cautious stance.
Technically, the pair remains above its 200 DMA near 1.3400, with the daily RSI around 60 suggesting positive momentum. However, resistance at 1.3430 continues to constrain gains, with a sustained break potentially opening the way towards 1.3441. Conversely, failure to overcome this level could encourage a retreat towards the 20 DMA and VWAP support area around 1.3300. We expect Thursday's BoE decision and accompanying guidance to be the principal catalysts for sterling, with the near term outlook remaining cautiously constructive provided the pair holds above its 200 DMA.

