EUR / USD
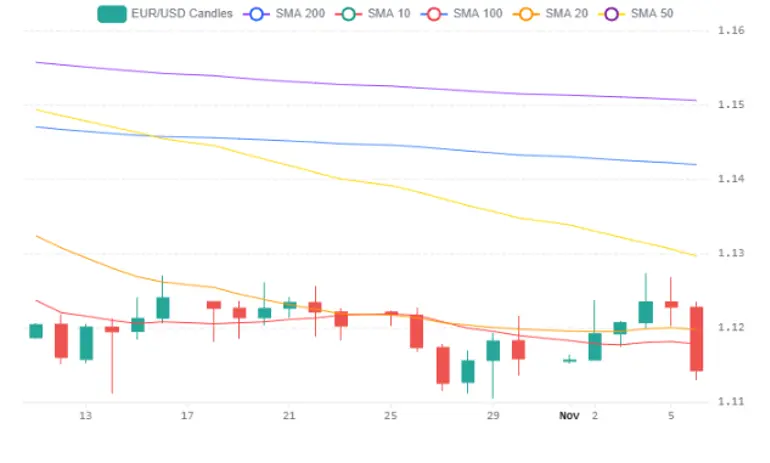
Source: Massive (polygon.io)
EUR/USD slid about 0.7% late last week, easing from a Thursday peak near 1.123 to settle around 1.114 at Friday's close after briefly tagging 1.113. The pair now trades below the 20-day moving average at 1.1192. The 50-day (about 1.1330) and 200-day (about 1.1538) averages both slope lower, and a daily RSI near 39 signals soft but not oversold momentum.
Fundamentals lean toward the dollar. October payrolls rose by 165,000, with 4.1% unemployment, upward revisions and the strongest wage gain since January, lifting the odds of a December Fed hike back toward the high 70s. Expectations for a December ECB hike have slipped to roughly 60% from 75%, even with euro-area inflation near a three-year high of about 4%, and sharper falls in French and German short-term yields tilt rate differentials against the euro.
The main counterweight is positioning: speculative net euro shorts sit at an 11-year extreme and gross shorts at record highs, leaving the pair prone to a sharp squeeze if US data disappoint. Tuesday's US CPI, expected to cool to 0.3% headline and 0.2% core, is the pivotal catalyst, with a soft print likely to revive the euro and an upside surprise reinforcing the dollar. Technically, the late-October trough near 1.1115 is the critical pivot. Holding it and reclaiming 1.12 would open a squeeze toward 1.128 and the 50-day near 1.13, whereas a decisive break would mark fresh yearly lows and expose 1.10.
USD / JPY
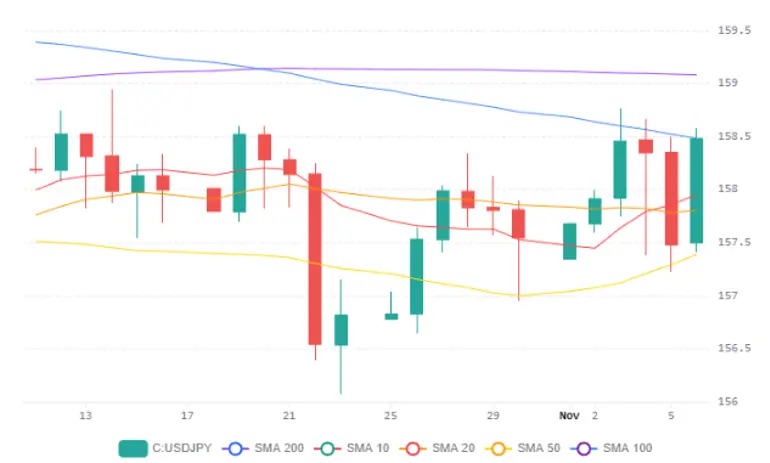
Source: Massive (polygon.io)
USD/JPY remains underpinned by a wide rate gap: US two-year yields sit roughly 2.8pps above Japanese equivalents, keeping yen-funded carry attractive after October payrolls rose a stronger-than-expected 165,000. That support is weakening, as a tech-led equity rout tightens US financial conditions and markets have cut the odds of a December Fed hike to about 70% from above 80%. In Japan, the Bank of Japan says underlying inflation has reached its 2% target, yet markets price only about 42% odds of a December hike, given an expected tenth straight monthly fall in household spending.
Technically, the pair recovered from an early dip toward 157.25 to finish near 158.48, up 0.43%, clearing the 20-day average near 157.98 and finding resistance at the 200-day moving average at 158.68, with RSI around 56 signalling firm but not stretched momentum. Meanwhile, the 157.40–157.95 band now acts as the first cushion. Sustained trade above 158.94 would open a test of 159.10 and potentially 160, whereas a rejection followed by a break below 157.40 would expose 156.35.
The main near-term risks are a soft reading from Tuesday's October CPI and a hawkish BOJ summary of opinions this week, either of which could narrow the differential and cap the rally, while persistent US price pressure, with producer prices at multi-year highs, would favour further dollar gains.
GBP / USD
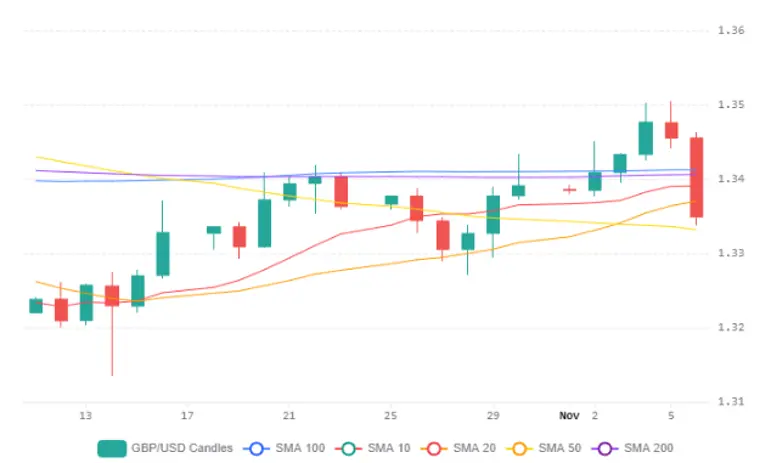
Source: Massive (polygon.io)
Cable sold off over the past few sessions, falling from near 1.345 to around 1.335. Heavy early-US trading briefly took it to 1.334 and erased most of the earlier push toward 1.350. The pair now sits below the 50-day and 100-day moving averages at 1.3358 and 1.3420, respectively, which act as overhead resistance, while the 20-day average at 1.3347 act as nearest support, and daily RSI reads a neutral 48.
Fundamentally, the pair pits two hawkish central banks against each other. The Bank of England has delivered its first hike since 2023, and Thursday's third-quarter GDP is expected to show growth quickening to about 0.7%, while October's 165,000 payrolls lifted odds of a December Fed hike to roughly 78%. Tuesday's US CPI, forecast at 0.3% headline and 0.2% core month on month, is the week's key swing factor, since a softer print could trim Fed tightening bets and favour sterling.
Holding the 1.33 confluence and reclaiming 1.34 would reopen the 1.350 swing high, whereas a decisive break below 1.33 exposes 1.326 and the October low near 1.315.
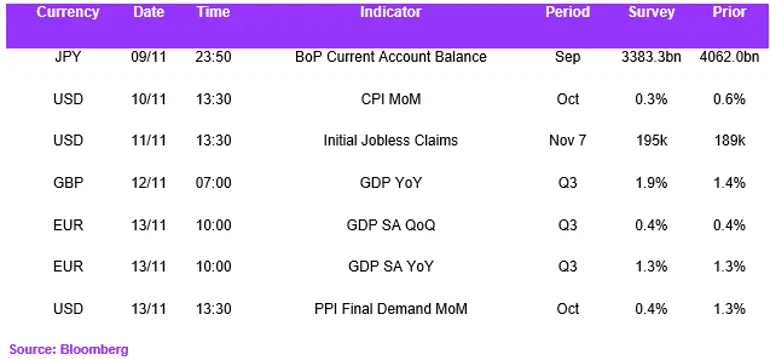
Economic Calendar