EUR / USD
Source: Massive (polygon.io)
EURUSD
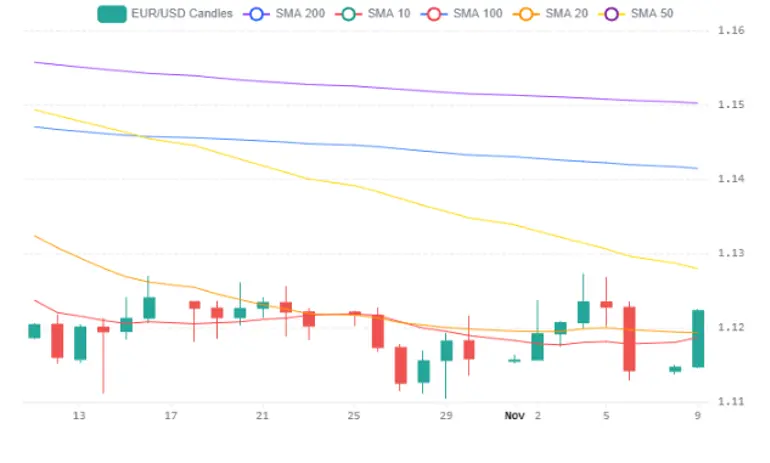
EUR/USD rebounded 0.8% on Monday from Friday's late-session low near 1.1135 to close around 1.1223. That move unwound much of the dollar rally sparked by October's stronger-than-expected US payrolls report of 165,000 jobs. Signals that Washington is unlikely to order fresh strikes on Iran sent crude sharply lower and reduced safe-haven demand for the dollar, while cheaper energy gives the import-dependent eurozone a direct terms-of-trade boost. German September exports rose 2.0% against 0.5% expected, and a narrower French-German yield spread added further support.
Monetary policy remains finely balanced: markets price roughly an 80% chance of a Fed hike at the December 8-9 meeting, while estimates for an ECB December hike range from about two-thirds to above 80% after October eurozone inflation of 4.0%. Over the medium term, heavy speculative dollar longs and a euro that looks cheap relative to short-term rate differentials favour the single currency.
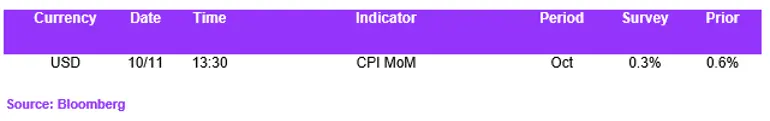
Technically, the daily RSI climbed from about 39 to 51, and the pair reclaimed its 20-day moving average around 1.12 – a key pivot zone. Holding above 1.12 opens resistance at 1.1286 and then the 1.130 level, while a slip back below 1.12 exposes the late-October low at 1.1115, where a decisive break would resume the six-month decline. Tuesday's October US CPI, expected at 0.3% month-on-month, is the immediate trigger: a hot print would revive the dollar, while a softer one would let euro fundamentals take the lead.
USD / JPY
Source: Massive (polygon.io)
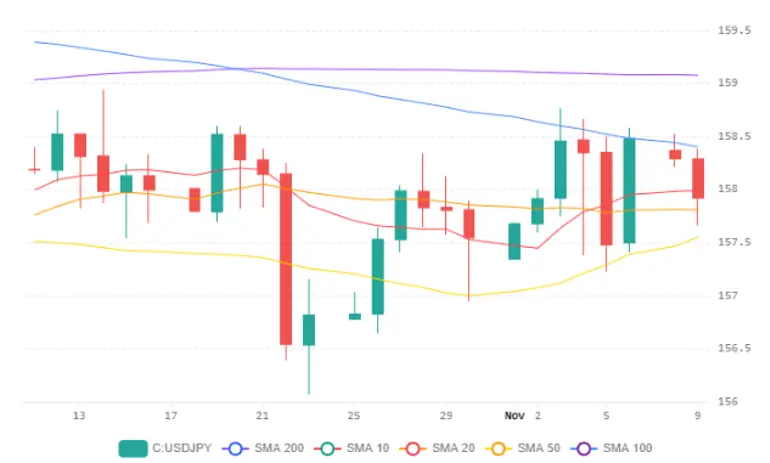
USD/JPY eased about 0.4% on Monday, from near 158.5 late Friday to roughly 157.9, and now sits near 157.95 and just above the 20-day SMA around 157.8, with a neutral daily RSI near 50.5 showing little conviction below the 50-day SMA at roughly 157.29. Holding the 157.7–157.8 cluster and reclaiming 158.5 would open a retest of the 158.9 monthly high and then 159.1, while a decisive break below the rising 50-day average near 157.5 would likely trigger momentum selling toward the 156.4 support zone set in late October.
Fundamentally, the dollar is underpinned by a strong US labour market: October nonfarm payrolls rose by 165,000 against expectations of 65,000, unemployment fell to 4.1%, and wage growth accelerated to 3.1% year over year. Markets now assign roughly an 80% to 83% probability to a quarter-point Fed hike at the December 8-9 meeting. Against that, markets price about a 70% chance that the Bank of Japan lifts rates from 1.25% on December 18, after Governor Ueda flagged upside risks to underlying inflation, which reached 2.4% in September on the core measure, though a softer September leading index tempers the urgency. Some strategists expect the BOJ to reach 2% or higher while the Fed stops around 4.00-4.25%, narrowing the policy gap by roughly 50 basis points over the coming year.
The yen also gains from a roughly 4% drop in crude oil on Middle East settlement hopes, and from official resistance to yen weakness after Japan's record intervention of about $50 billion in a single day in late July and the first coordinated yen-buying operation with the United States since 1998. This week's US October inflation data is the key near-term catalyst: a firm print validating a Fed hike would favour a push toward 158.5–159.1, while a soft one would strengthen the case for narrowing rate differentials and a test of 157.5 and below.
GBP / USD
Source: Massive (polygon.io)
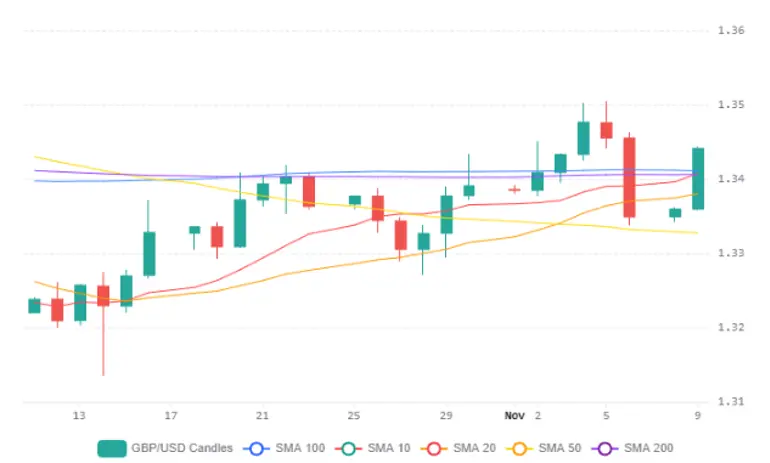
Sterling recovered most of Friday's losses on Monday, with GBP/USD climbing about 0.7% from the weekly low near 1.335 to around 1.344. Safe-haven demand for the dollar faded as AI-stock concerns eased and oil prices fell sharply. Speculative positioning that is already heavily long the dollar leaves the greenback exposed to further corrections if risk appetite holds.
The Bank of England raised Bank Rate by 25 basis points to 4% last week on an 8–1 vote and signalled further tightening unless the Middle East conflict de-escalates, though a sustained drop in energy prices could strengthen the one-and-done camp. In the US, October's 165,000 payrolls gain has pushed odds of a December Fed hike above 80%, making Tuesday's US CPI and Thursday's UK third-quarter GDP (expected around 0.7%) the key near-term catalysts.
Technically, the pair has reclaimed the 20- and 200-day averages near 1.34, with daily RSI near 58 signalling firmer but not overstretched momentum. Holding 1.34 opens a retest of the 1.35 ceiling and, on a decisive break, the late-August high near 1.366, while failure there would expose the 1.33 zone, then 1.327 support and the October floor around 1.315.
Economic Calendar