EUR / USD
Source: Massive (polygon.io)
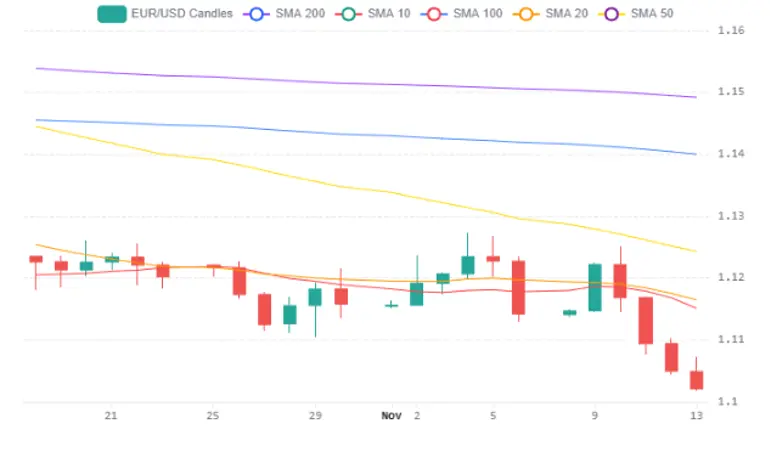
EUR/USD extended its slide by about 0.3% to around 1.1021, touching fresh one-year lows near 1.1019 and leaving the pair more than 5% below its level a year ago. Hotter-than-expected US October consumer and producer inflation has left a December Federal Reserve hike close to fully priced, with the 10-year Treasury yield back above 5% and the broad dollar at its strongest in roughly 19 months. The ECB is also expected to raise its deposit rate in December, but this has not offset the widening rate gap: markets see the Fed tightening more and for longer, and eurozone growth slowing to 0.4% in the third quarter limits how hawkish the ECB can credibly be. Safe-haven demand driven by a sell-off in AI-linked equities and a deep crypto rout further strengthens the dollar's position.
The pair trades well beneath its 20-day average near 1.1170 and other moving averages, with daily RSI near 32 hovering just above oversold territory. Stretched momentum could spark short covering through 1.1073 toward the 1.1165–1.1177 cluster, while failure to recover 1.1043 and a sustained break under 1.1019 would likely extend losses toward 1.0950.
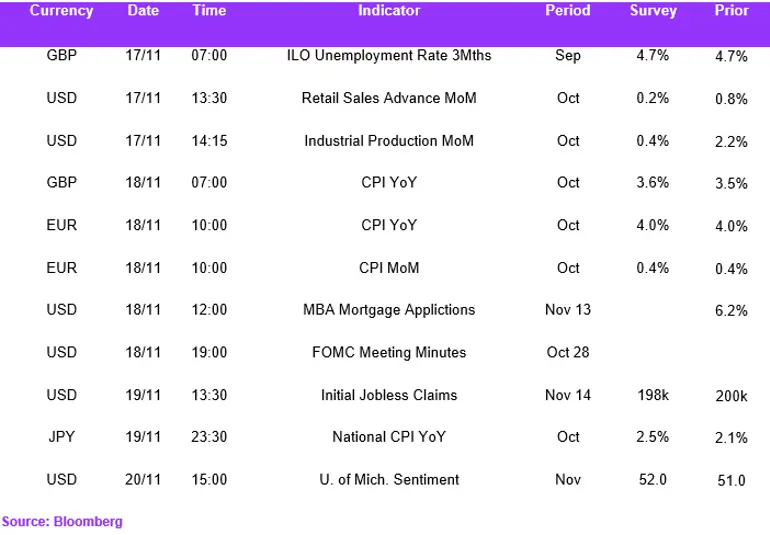
Key catalysts this week include a speech by Fed Chair Kevin Warsh, US retail sales, the FOMC minutes alongside eurozone inflation data, and US jobless claims. Forecasts that US core inflation will ease into 2027 suggest the dollar's rate-driven advantage may eventually fade, but near-term forces continue to favour the greenback over the euro.
USD / JPY
Source: Massive (polygon.io)
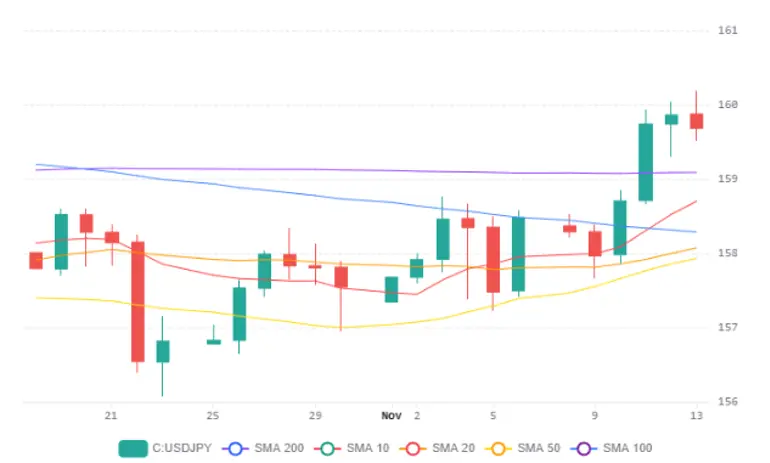
Monetary divergence still favours the dollar: the Federal Reserve held at 3.75%–4.00% in late October with two dissents in favour of a hike, and a firmer October CPI has markets pricing a December increase as near-certain, lifting the two-year Treasury yield about 35 basis points in a week and the 10-year back above 5%. In Japan, October wholesale inflation of 7.1% and a board dissent in favour of 1.5% strengthen the case for a Bank of Japan hike at its December 17–18 meeting, yet parallel 25-basis-point moves would still leave the policy gap above 2.5 percentage points.
The main counterweight is intervention: Tokyo spent roughly $96 billion defending the yen in late July and early August, and senior officials have renewed warnings, though the summer operation's effect faded within about three months. This week's catalysts include Japan's third-quarter GDP, where consumption is expected to contract, October core inflation, US retail sales and the FOMC minutes, with firm US data likely to revive talk of a larger Fed hike ahead of the November 25 PCE release.
Technically, the pair has been pinned in a tight band just below 160, briefly probing about 160.2 on the 13th before settling near 159.7. A daily RSI near 63 and trading above the rising 200-day (about 158.75), 20-day (near 158.20) and 50-day (roughly 157.54) moving averages keep momentum constructive, and a decisive break above 160.2 while 159.1 holds would open 161 and potentially 162. Repeated rejection below 160, especially with intervention risk at these levels, could drag the pair through 159.1 toward the 158 cluster and support near 157.3. On balance, the bias favours the dollar, but official action or a hawkish BoJ surprise poses meaningful two-way event risk.
GBP / USD
Source: Massive (polygon.io)
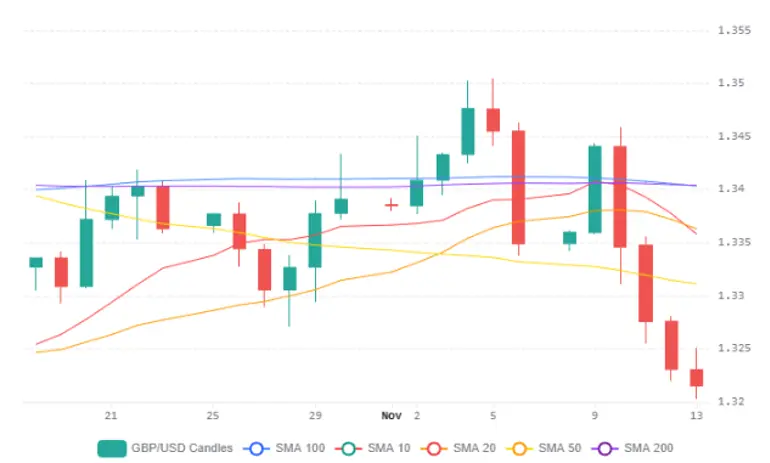
GBP/USD slipped about 0.2% to roughly 1.3215 today, extending a near-2% slide from the early-November peak near 1.35 and leaving the pair below its 50-, 20- and 200-day moving averages (1.3334, 1.3360 and 1.3360). The main driver is a widening policy gap: hotter-than-expected October US consumer and producer inflation, plus two dissents favouring a hike at the October FOMC, have markets pricing a December quarter-point Fed hike as near-certain, while long-dated Treasury yields above 5% and broad risk aversion add a defensive bid for the dollar.
The Bank of England's move to a 4% policy rate and a firmer 0.7% third-quarter growth print offer sterling some support, though softening housing and higher mortgage costs may limit how far the Bank can lean hawkish. The key tests this week are Wednesday's UK October CPI and Governor Bailey's speeches, alongside Tuesday's US retail sales, Wednesday's FOMC minutes and the November 25 PCE release.
Technically, a rejected push toward 1.325 and a daily RSI near 38 point to momentum that is weakening but not yet oversold, so bulls need to defend 1.32 and reclaim 1.330–1.331 to target 1.334–1.336. A break below 1.32 exposes the mid-October trough near 1.315 and then the yearly lows around 1.305, and unless UK inflation surprises firmly higher or US data cools, risks remain tilted toward further sterling weakness.
Weekly Economic Calendar