EUR / USD
Source: Massive (polygon.io)
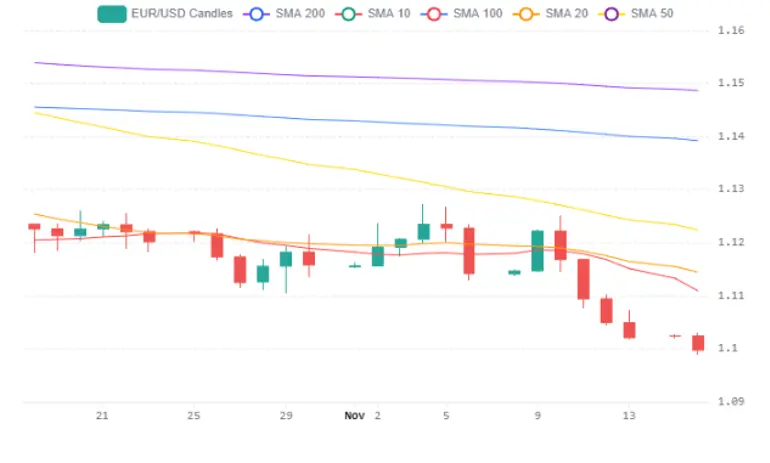
EUR/USD extended its slide into Monday, slipping about 0.2% to roughly 1.0998 and printing a fresh twelve-month low near 1.099, which leaves the pair down more than 5% on the year and well below its late-January peak around 1.204. The main driver is monetary policy divergence: a hotter-than-expected October US CPI (headline 0.4%, core 0.3%) and hawkish Federal Reserve commentary have lifted the dollar index to its strongest level since April 2025, and futures now treat a December Fed hike as virtually certain. The ECB is also expected to hike in December, taking the deposit rate to 2.75%, but swaps price roughly 90 basis points of US tightening over the next year versus about 70 for the ECB, and the US-German 10-year spread has widened to around 1.75 percentage points.
Eurozone fundamentals offer little offset, with third-quarter growth slowing to 0.4%, September industrial output 1.5% below a year earlier, and French fiscal slippage adding a risk premium. An AI-led equity selloff has further boosted demand for dollar liquidity, while options show persistent demand for protection against euro weakness, indicating positioning already leans heavily toward the dollar.
Technically, the trend is decisively bearish, with spot below the 20-day average near 1.1160, and the 50-day near 1.1280, though a daily RSI near 30 signals oversold conditions. A defence of the 1.099–1.100 floor could spark a relief rally through 1.103 toward the 1.1145–1.117 cluster, whereas a sustained break below 1.099 opens a path to 1.095 and potentially 1.090. On balance, the bias favours further dollar strength while US inflation stays firm, with reversal risk concentrated in Tuesday's retail sales, Wednesday's FOMC minutes and any further drop in oil prices that softens Fed hike pricing.
USD / JPY
Source: Massive (polygon.io)
USD/JPY is caught between a hawkish Federal Reserve and a Bank of Japan still committed to normalisation. Hotter-than-expected October US inflation has markets treating a 25-basis-point December Fed hike as nearly certain, with 10-year Treasury yields above 5% and the dollar index at its strongest since April 2025. In Japan, third-quarter GDP contracted 0.1% annualised, yet a 2.4% GDP deflator, solid AI-related capital expenditure and underlying inflation at target keep pricing for a December 18 BoJ hike near 85%.
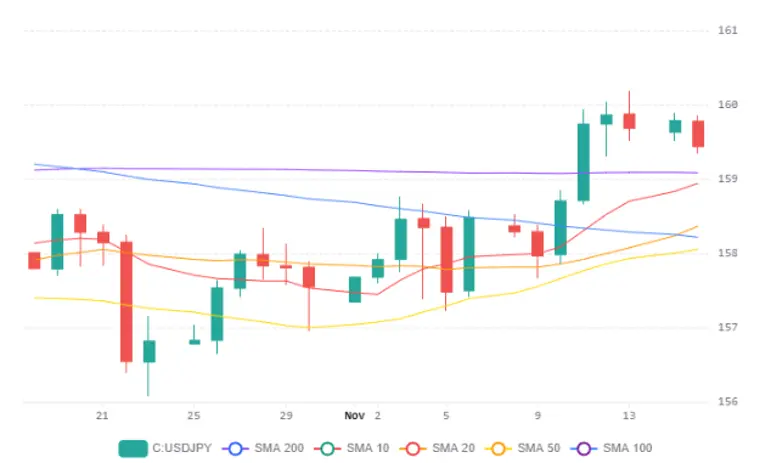
Today the pair slipped about 0.2% to near 159.43 after failing to clear the 160.02 resistance from late last week. Buyers defended the 159.20 support. Momentum remains constructive, with daily RSI near 59 and price above a rising support cluster of the 20-day average (158.26), and the 100-day average (158.94). Holding above 159.10–159.20 favours a retest of 160.02 and possibly the 163–164 summer highs, while a clean break lower exposes 158.40–158.05 and then 157.26 and 156.29.
Because the rally rests on broad dollar demand rather than yen-specific weakness, dovish Fed pushback, falling oil prices or risk-off equity moves could trim it.
GBP / USD
Source: Massive (polygon.io)
GBP/USD is under pressure as the US dollar trades at its strongest level since April 2025, lifted by hotter-than-expected October inflation, hawkish Federal Reserve commentary that has markets treating a December 9 rate hike as essentially certain, and ten-year Treasury yields holding above 5%. Sterling has hawkish support of its own after the Bank of England raised Bank Rate to 4% this month and signalled further tightening. However, a Fed hike that the Bank does not match before its December 17 decision would lift the top of the US policy range above Bank Rate and tilt the yield gap toward the dollar. This week's UK labour data and October inflation, expected to rise toward 3.6% to 3.7%, are the key tests of whether the Bank can keep pace.
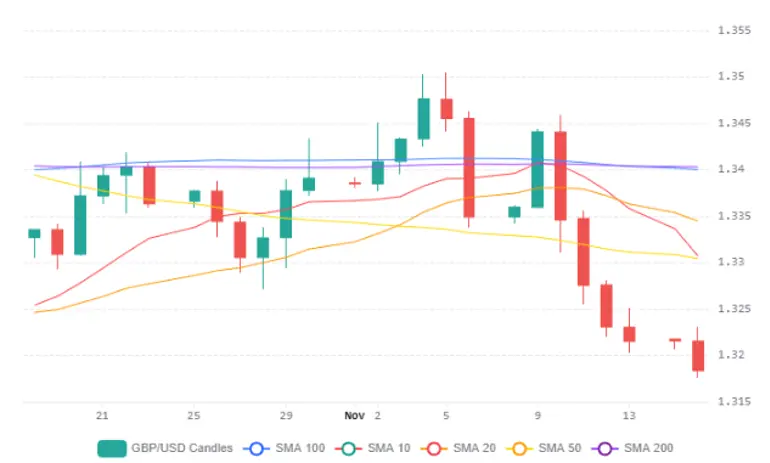
Cable has shed roughly 2% over the week, extending a slide from its early-November peak near 1.350, and today sellers rejected a push toward 1.322 and drove the pair to a fresh low around 1.318. It now trades beneath the 50-day SMA near 1.333, the 20-day SMA at 1.3354, while a daily RSI near 36 shows weakening momentum that is not yet oversold.
If buyers defend the October low around 1.315, a short-covering bounce could reclaim 1.330 and retest 1.334, whereas a clean break below 1.315 would expose the late-2025 low near 1.304.
Economic Calendar