EUR / USD
Source: Massive (polygon.io)
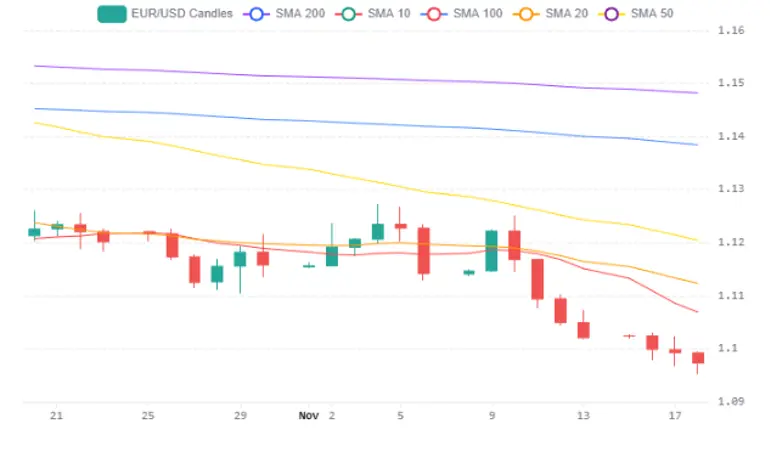
EUR/USD slipped about 0.22% over the past day to 1.0974 after touching a one-year low near 1.0954 on Wednesday, extending a weekly decline of more than 2% and a twelve-month drop of over 5%. The pair trades below all its major averages, including the 20-day SMA at 1.1124, the 50-day at 1.1243 and the 200-day at 1.1506, all still falling, while a daily RSI near 29 signals oversold conditions.
The main driver is monetary policy divergence. Minutes from the Fed's October meeting showed almost all participants favouring further hikes, and markets fully price a December quarter-point move and about 75 basis points of tightening over the next year, with long-term Treasury yields near 5%. The ECB is also expected to hike in December and again by April after October HICP reached 4.0% with core at 2.6%. However, that inflation is largely energy-driven and squeezes incomes in an import-dependent region, so ECB tightening looks defensive rather than supportive of the euro. French fiscal strain, uncertainty over the succession after Lagarde's early departure in February, and geopolitical anxiety around the Shenzhen summit and the Iran conflict add to safe-haven demand for the dollar.
A decisive break below 1.0950 would confirm the downtrend and open the way toward 1.0900, while stretched momentum could instead spark a short-covering bounce toward 1.1070 and the 1.1120–1.1150 band, where rallies are likely to be sold. Falling oil prices, a more incremental Fed pace, or the dollar running short of fresh catalysts after so much tightening is priced in are the chief risks to this view, but the near-term balance still favours the dollar.
USD / JPY
Source: Massive (polygon.io)
USD/JPY remains anchored by wide policy divergence: markets fully price a 25-basis-point Federal Reserve hike in December and roughly 75 basis points of further tightening over the next year, keeping the US-Japan 10-year yield gap near two percentage points. The Bank of Japan is also tightening, with most economists expecting a December hike to 1.50% and another to 1.75% by end-March, supported by core inflation above 2% and wage gains near 5%. The third-quarter contraction and a roughly 7% monthly slide in Japanese equities still leave some risk of a December pause.
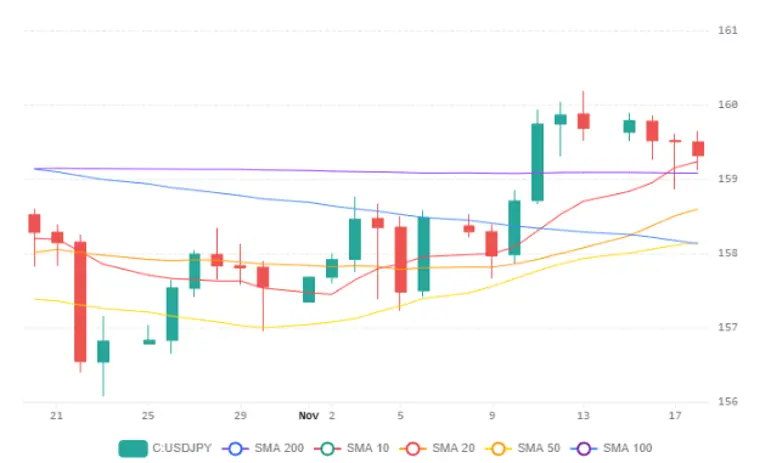
The pair closed the latest session barely changed at about 159.32, trading within an unusually tight 0.33% range. The 200-day moving average near 158.84 held as a floor, while the 20-day average (158.51), the 50-day average (157.86) all sit below spot, and an RSI near 58 signals firm but not stretched momentum. Holding 159.10 and reclaiming 159.65 would target last week's high near 160.00 and then the 163–164 summer peaks, while a sustained break below 159.10–158.90 exposes 158.60, the 158.15–158.30 zone and eventually 157.35.
Rate differentials favour continued dollar strength, but the nearly $100 billion Japanese authorities have already spent defending the yen, along with ongoing official warnings, makes intervention a key cap on any push above 160.
GBP / USD
Source: Massive (polygon.io)
GBP/USD's slide to a six-month low near 1.3150 reflects broad dollar strength more than pound-specific weakness, with hawkish Federal Reserve signals lifting the dollar index to roughly a nineteen-month high. The October FOMC minutes showed almost all participants favouring further hikes, and Governor Waller called for a half-point move in December or clear guidance toward faster tightening in 2027, leaving markets fully pricing a December increase.
In the UK, October CPI rose to a one-year high of 3.6%, but core inflation held at 2.8%, services inflation undershot Bank of England projections, and wages and payrolls weakened, trimming December BoE hike odds to about 80% and leaving policy divergence in the dollar's favour.
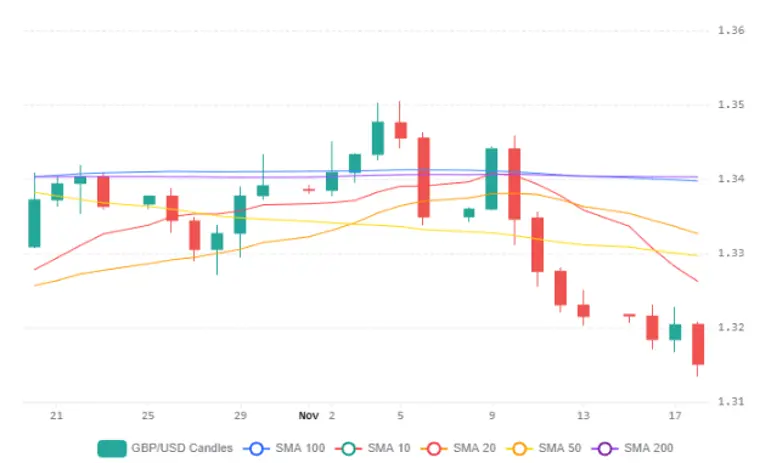
Cable fell about 0.4% over the past day from 1.3208, extending a weekly decline of over 2% from highs near 1.3454. It is probing support near 1.3144 after briefly touching 1.3136, and a daily RSI near 34 shows deepening bearish momentum that is not yet oversold. The pair also trades below every key moving average, from the 50-day near 1.3311 to the 200-day near 1.3321.
A decisive hourly close below 1.3136 would expose the November 2025 low near 1.3045, while a firm defence of 1.3140 could spark short-covering toward 1.3296–1.3311 and then the 1.3326–1.3333 cluster. Sterling's resilience against the euro, stronger-than-expected UK growth and falling energy prices could cushion further downside if US data cool.
Economic Calendar