EUR / USD
Source: Massive (polygon.io)
The EUR/USD pair remains under sustained bearish pressure, driven by a widening transatlantic monetary policy divergence after the Federal Reserve raised rates by 25 basis points to 3.75%–4.00% while the ECB's deposit rate sits notably lower at 2.50%, despite a hike. The resulting yield differential — approximately 150 basis points between U.S. 10-year Treasuries at 5.00% and German bunds at 3.52% — continues to pull capital toward dollar-denominated assets, creating a structural headwind for the euro. Persistent U.S. inflation, with headline CPI at 3.4% and PPI surging at 5.41% annually, reinforces expectations for at least one additional Fed hike, further entrenching the dollar's yield advantage.
On the European side, the ECB faces a near-stagflationary bind with projected growth of just 0.9% against 3.0% inflation, severely limiting its capacity to tighten aggressively without deepening economic weakness. Elevated crude oil prices above $100 per barrel disproportionately burden the energy-import-dependent eurozone, while political uncertainty in Germany adds a further layer of risk to European sentiment.
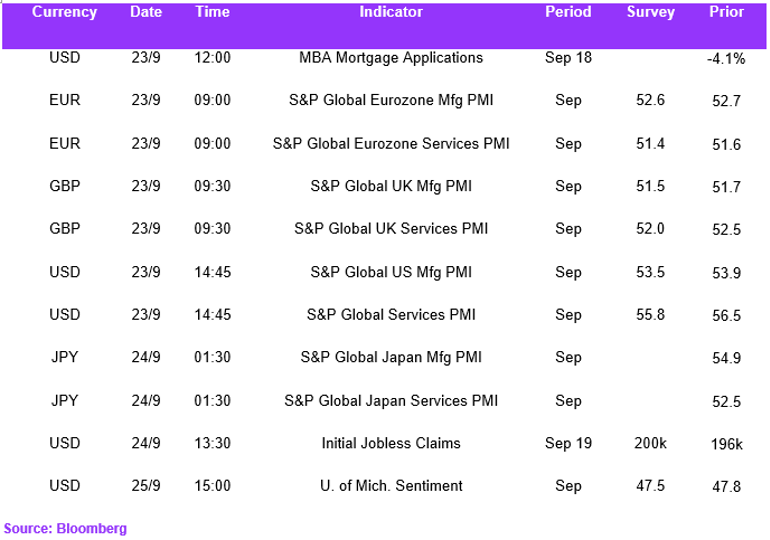
From a technical standpoint, EUR/USD is trading at approximately 1.1480, well below all major moving averages — the 200-day SMA near 1.1600, the 50-day at 1.1560 — confirming the prevailing downtrend. The daily RSI at 33 signals oversold conditions that could trigger a short-term mean-reversion bounce toward the 1.1560–1.1600 resistance cluster, though tentative support at 1.1455 remains the critical line in the sand. A failure to hold that floor would expose the yearly support at 1.1356, and absent a meaningful decline in U.S. inflation or a surprising upturn in eurozone growth data, the macro and technical backdrop broadly favours continued dollar strength against the euro.
USD / JPY
Source: Massive (polygon.io)
The USD/JPY pair finds itself at a critical juncture, caught between powerful opposing forces as both the Federal Reserve and the Bank of Japan tighten policy at divergent speeds. The Fed's 25 basis point hike to 3.75%–4.00%, combined with roughly 55% market-implied odds of another October increase and the 10-year Treasury yield breaching 5%, continues to reinforce the interest rate differential that underpins dollar strength against the yen. While the BOJ's historic rate increase to 1.25%—a 31-year high—signals genuine normalization, Governor Ueda's reluctance to commit to a specific terminal rate or tightening schedule left markets unconvinced, triggering yen weakness despite the hawkish move.
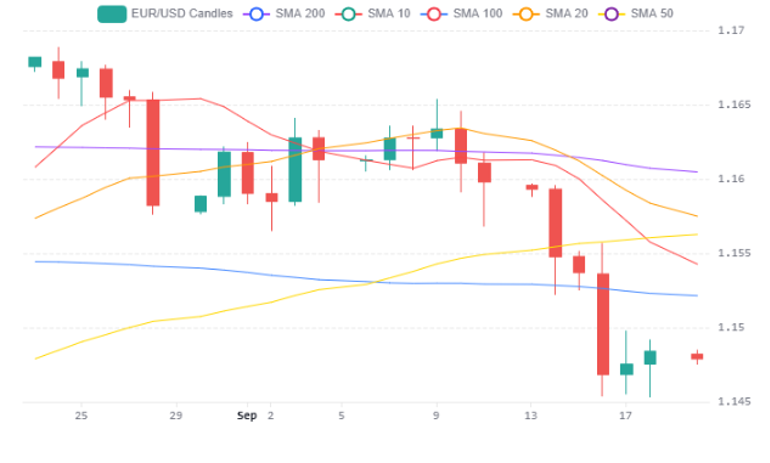
From a technical perspective, the pair is trading around 157 after an unusually volatile session that saw a 1.4% rally toward 158 before reversing sharply back to 156.75, with the daily RSI recovering to approximately 50 after spending the prior month in bearish territory below 40. The failed push at the 50-day SMA near 158 may constitute a lower high within the broader three-month downtrend from the July peak near 164, while support at the 20-day SMA around 156 remains the key level to hold for bulls.
Intervention risk represents the most significant near-term asymmetric threat to dollar-long positions, as the BOJ's rate checks with currency traders during New York hours and the record 15.4 trillion yen spent on intervention between late July and August demonstrate the Ministry of Finance's willingness to act aggressively, particularly during the upcoming Silver Week holiday when thin liquidity amplifies the impact of any operations. Traders should closely monitor whether the pair can sustainably reclaim the 158 level or instead breaks below 156, which would reopen a path toward the early-September low around 153 and signal that the broader bearish trend remains intact.
GBP / USD
Source: Massive (polygon.io)
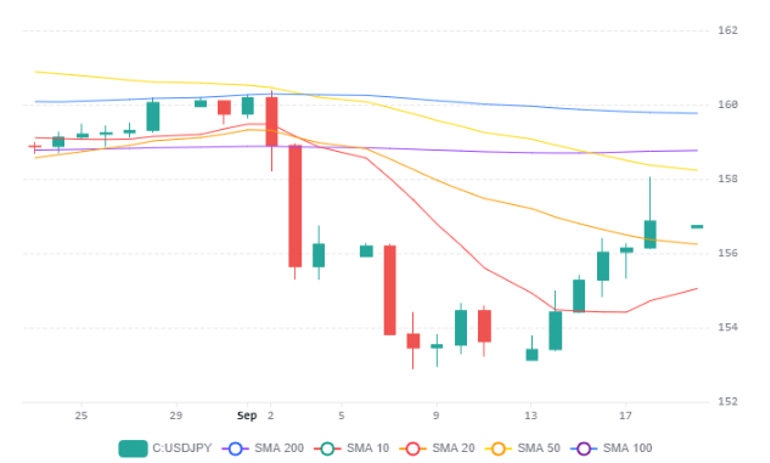
GBP/USD is trading at approximately 1.339, pinned below key moving averages including the 200-day SMA at 1.340, the 20-day SMA at 1.345, with the daily RSI at a depressed 35 signalling oversold conditions following a sharp dip toward 1.334 before a partial intraday recovery. The technical picture presents a binary setup: a sustained push above the 200-day SMA at 1.340 could trigger short-covering toward 1.345, while failure at that level and a break below 1.334 would expose the pair to deeper losses toward 1.328.
The macro backdrop tilts bearish for the pound, driven by a clear monetary policy divergence—the Fed hiked rates to 3.75%–4.00% and signalled further tightening, while the Bank of England held steady at 3.75%, leaving its next move contingent on the trajectory of an energy shock that disproportionately impacts the UK as a net importer. UK gilt yields have surged to multi-decade highs, reflecting fiscal strain under new leadership, with rising government borrowing costs feeding through to higher mortgage rates and compounding household pressures from an anticipated near-£500 annual increase in energy bills.
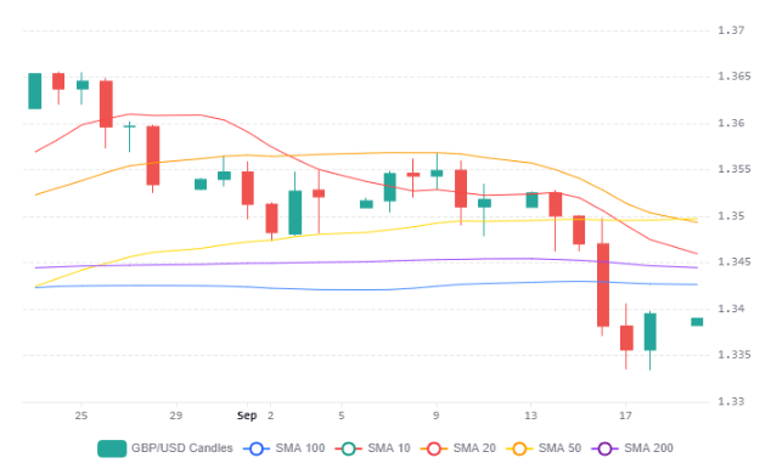
This week's flash PMI releases on both sides of the Atlantic will be pivotal; any evidence that oil prices above $100 per barrel are eroding UK economic activity could undercut expectations for further Bank of England tightening and weigh heavily on sterling. The combination of a hawkish, data-dependent Fed, deteriorating UK fiscal credibility, and geopolitical wildcards including the Trump-Xi summit—where any escalation in trade tensions could amplify safe-haven dollar demand—creates an asymmetrically challenging environment for GBP/USD, with risks skewed to the downside unless the oversold technical setup catalyses a meaningful corrective bounce.
Economic Calendar