


EUR / USD
Source: Massive (polygon.io)
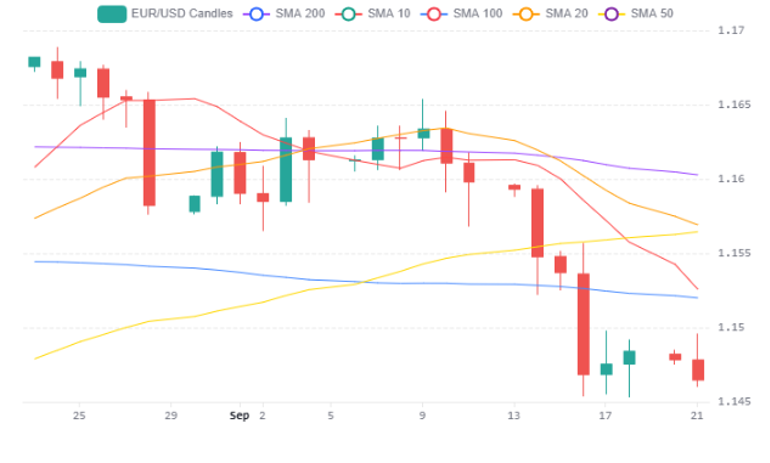
The EUR/USD pair remains under pressure, drifting lower within a narrow range from roughly 1.1486 to 1.1465 over recent sessions, weighed down primarily by widening monetary policy divergence between the Fed and the ECB. The Fed’s recent 25bps hike to 3.75–4.00%, reinforced by hawkish rhetoric from officials such as Musalem and Goolsbee, has strengthened the forward-path narrative. Markets have already priced in as much as 31bps of hikes by year-end, reflecting a hawkish bias; in our view, even if a more dovish tone comes through from officials, markets may be reluctant to price it in fully. Fed speakers could still add macro noise and skew flows, particularly around the future path of interest rates, supporting the dollar’s resilience against the euro.
From a technical standpoint, the price now sits well beneath the cluster of key moving averages, with the 200-day, 50-day and 20-day SMAs all converging near 1.1600, confirming a decidedly bearish posture. The daily RSI has fallen to approximately 31, signalling deeply oversold conditions. A bearish continuation scenario would see sustained selling pressure drive a break below the 1.1460 lows and accelerate the decline toward yearly support near 1.1356, though oversold readings could attract tactical dip buyers and trigger a mean-reversion bounce back toward 1.1600.
Beyond rate differentials, the energy shock continues to erode Europe’s terms of trade more acutely than America’s, compounding the euro’s vulnerability even as Brent crude has pulled back below $100 per barrel. In the meantime, we expect oil prices and broader geopolitical sentiment to remain the main drivers of momentum this week. Safe-haven demand linked to the Iran conflict and stronger relative US economic momentum further bolster the dollar, while the upcoming Trump-Xi summit introduces event risk that could shift sentiment rapidly if trade or geopolitical tensions de-escalate. While European growth has proven more resilient than anticipated and some forecasters expect an unusually narrow trading range ahead, the confluence of hawkish Fed policy, bearish technicals and geopolitical uncertainty keeps the near-term bias tilted toward further EUR/USD downside.
USD / JPY
Source: Massive (polygon.io)
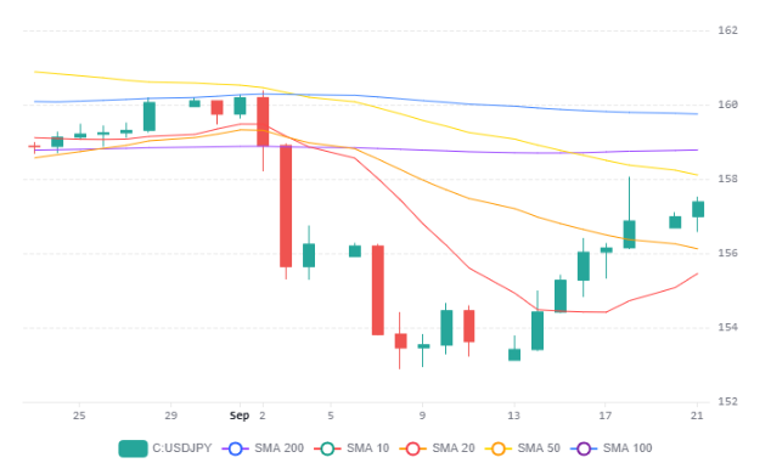
The USD/JPY pair continues to grind higher, advancing roughly 0.3% over the past three sessions to 157.39, supported by a persistent US-Japan yield differential that favours the dollar despite both central banks tightening simultaneously. The Fed’s 25bps hike and hawkish forward guidance, with markets pricing more than a 50% probability of another October increase, have overshadowed the Bank of Japan’s own historic rate rise to 1.25%. Two dissenting BoJ votes and tepid forward guidance disappointed yen bulls, widening the communication asymmetry between the two institutions.
From a technical standpoint, the pair now trades above its 20-day SMA near 156 and short-term resistance around 157.05, with the daily RSI recovering to 54. However, it remains capped beneath the 50-day SMA at 158 and the 200-day SMA around 159, which have contained upside attempts throughout the prior month. A sustained break above 158 would open a path toward the 159 zone, while rejection at that level risks a retreat back toward the 20-day SMA near 156 and potentially the September low around 153.
Intervention risk remains the critical wildcard, as Japanese authorities have reportedly conducted rate checks — a widely recognised precursor to direct action — and the Silver Week holiday closure through Wednesday creates the thin liquidity conditions under which officials could act with maximum impact. However, we believe authorities may still be reluctant to intervene at these levels. For now, the Fed hike outweighs the BoJ move, while retail participation in the carry trade remains a key reason behind continued yen weakness after previous intervention concerns.
Structural headwinds for the yen persist as well, with Brent crude’s surge toward $100 per barrel forcing Japan to sell yen for dollar-denominated energy imports, while US 10-year Treasury yields near 5% reinforce the dollar’s carry advantage. Traders should watch speculative positioning closely, as the record pace of bullish yen bets in futures markets could amplify any intervention-driven reversal and leave the pair vulnerable to sharp dislocations in either direction.
GBP / USD
Source: Massive (polygon.io)
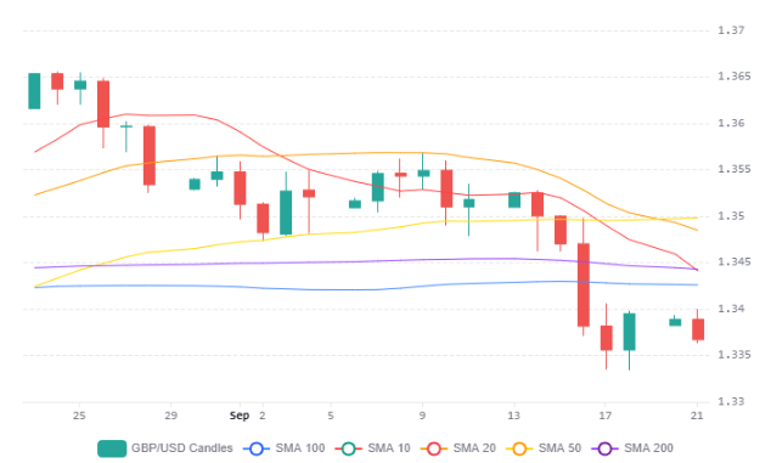
GBP/USD is trading under sustained bearish pressure, drifting lower to approximately 1.3368 and sitting beneath a cluster of overhead resistance formed by the 200-day SMA near 1.3400 and the 20-day and 50-day SMAs converging around 1.3500. The primary driver remains widening monetary policy divergence: the Fed’s recent hike to 3.75–4.00%, coupled with hawkish forward guidance from multiple officials, contrasts sharply with the BoE’s decision to hold rates steady, leaving sterling at a clear yield disadvantage. Fed speakers could still add macro noise around the future path of interest rates, keeping the dollar supported in the near term.
The geopolitical backdrop adds another layer of complexity, as the Iran conflict has pushed Brent crude above $100 per barrel, fuelling cost-push inflation that paradoxically supports dollar haven demand even as it weighs on global growth. Monday’s roughly 4% retreat in oil prices on hopes for diplomatic progress at the UN General Assembly offered fleeting relief, briefly lifting the pair toward 1.3400 before aggressive selling during the London-New York overlap drove it back to fresh lows near 1.3365 on heavy volume.
From a technical standpoint, the daily RSI at approximately 33 signals deeply oversold conditions that could attract dip buyers and spark a mean-reversion rally toward 1.3400. However, sustained failure to reclaim that level risks opening the door to 1.3280 support and potentially the June lows near 1.3150. Key near-term catalysts include September’s preliminary PMI readings, which will shape BoE rate expectations, and the Trump-Xi summit on Thursday, whose implications for global trade tensions and risk appetite could materially shift the pair’s trajectory.


