EUR / USD
Source: Massive (polygon.io)
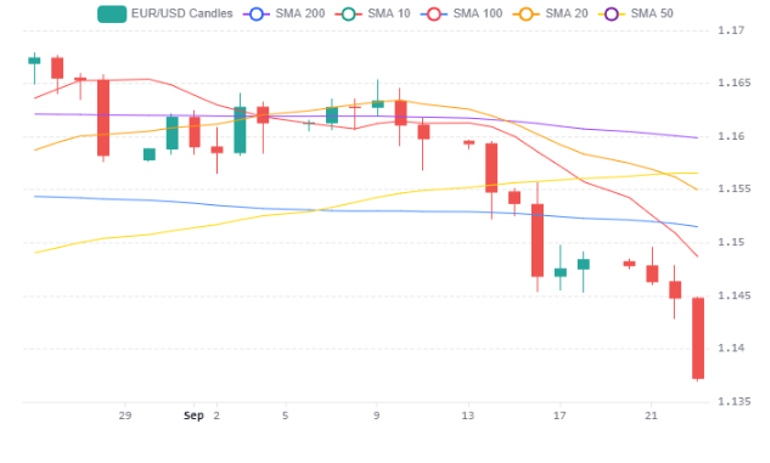
The EUR/USD pair is under intense selling pressure, declining approximately 0.62% over the past 24 hours to trade near 1.1377, its lowest level in over a month and approaching the yearly trough of 1.1329 set in late June. The primary catalyst remains a surging U.S. dollar, fuelled by a continued hawkish statements from Fed policymakers and unexpectedly strong U.S. economic data, with the flash Composite PMI hitting 58.4—its highest since July 2021—propelling market-implied odds of an October rate hike to roughly 70%. While the Eurozone flash Composite PMI's surprise improvement to 53.1 suggests some underlying resilience, this has been overwhelmed by the magnitude of the U.S. data beat and the resulting dollar strength.
The widening transatlantic rate differential is the structural engine of euro weakness. While the ECB also delivered a 25bps hike in September, its forward guidance has been markedly more cautious, with Chief Economist Lane signalling that future decisions will involve balancing competing forces. U.S. 10-year Treasury yields have rocketed above 5.10%, their highest since 2007, further eroding the euro's relative yield appeal and reinforcing dollar demand.
From a technical standpoint, the daily RSI has plunged to approximately 22, signalling deeply oversold conditions, with price trading well beneath the 200-day, 50-day, and 20-day SMAs—all clustered in the 1.15–1.16 zone—confirming the severity of bearish momentum. Geopolitical risks compound the euro's vulnerability, as elevated oil prices following continuously heightened U.S.-Iran tensions disproportionately damage Europe's terms of trade and economic outlook given its greater energy import dependence. A failure to hold the 1.1329 June low could open the door to an accelerated decline toward the 1.1280–1.1300 zone, though the extreme oversold RSI reading leaves room for a tactical mean-reversion bounce should upcoming U.S. data disappoint.
USD / JPY
Source: Massive (polygon.io)
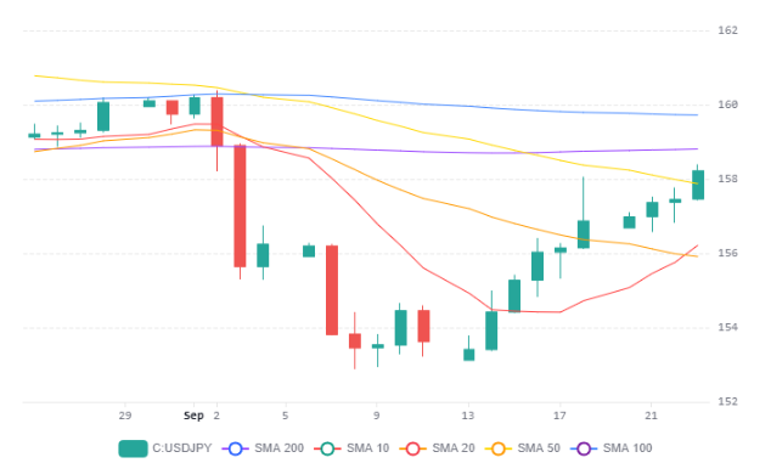
USD/JPY has rallied decisively over the past 24 hours, climbing roughly 0.6% to 158.27, with the daily RSI surging to approximately 59 from a prior-month average near 42, reflecting a sharp shift in momentum after the pair bottomed near 153 in early September. The advance carried price above the 50-day and 20-day moving averages but stalled just beneath the critical 200-day SMA at approximately 158.80, a level that will likely determine the pair's near-term directional bias.
The fundamental backdrop remains firmly tilted toward dollar strength, driven by a widening policy rate differential of roughly 275 basis. Rising U.S. Treasury yields — with the 2-year near 4.90% and the 10-year testing 5.10% — continue to incentivize yen-funded carry trades, and market-implied odds of another Fed hike have climbed to approximately 70% following a robust Composite PMI reading of 58.4. Geopolitical risk compounds the yen's vulnerability, as the Iran conflict has driven Brent crude up 37% since February and pushed Japan's inflation outlook higher through imported energy costs amplified by currency weakness.
A sustained break above the 200-day SMA near 159 could open a path toward prior resistance around 161, particularly if U.S. data continues to outperform and the Fed maintains its hawkish posture. However, Japanese authorities have intensified intervention signals — including rate checks and unprecedented coordination with the U.S. Treasury — and the closure of Japanese markets for a holiday creates low-liquidity conditions that could serve as a catalyst for official action, representing the most immediate downside risk to the pair's bullish technical setup.
GBP / USD
Source: Massive (polygon.io)
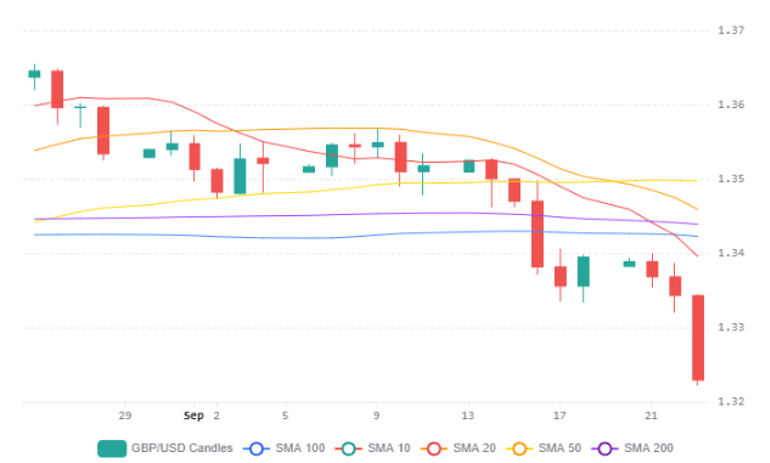
GBP/USD has suffered a sharp 0.9% decline over the past 24 hours, falling from around 1.3350 to 1.3229 in a nearly uninterrupted selloff driven by a broad-based dollar rally. Surging U.S. Treasury yields and a remarkably strong flash U.S. Composite PMI have amplified expectations for continued Fed tightening, with markets now pricing roughly a 70% probability of another 25-basis-point hike at the October FOMC meeting. Hawkish rhetoric from Fed Governor Michael Barr, who explicitly signalled further rate hikes are likely needed, has further reinforced the dollar's momentum.
The UK macro backdrop offers little counterweight, as September's flash Services PMI slipped to 51.7, undershooting consensus, while the economy faces headwinds from rising energy costs, weakening labour demand, and fiscal uncertainty ahead of the Autumn Budget. Technically, the pair has broken decisively below all key moving averages — including the 200-day SMA near 1.3400 — with the daily RSI plunging to approximately 23, signalling deeply oversold conditions that could catalyse a near-term mean-reversion bounce toward 1.3400.
However, the widening rate differential outlook favouring the dollar, combined with geopolitical uncertainty and the risk that the Bank of England disappoints market expectations for aggressive tightening should UK economic momentum continue to fade, suggests that any relief rally is likely to be shallow and that the path of least resistance for cable remains lower, with a failure to reclaim 1.3300 opening the door toward the yearly low near 1.3015.
Economic Calendar