EUR / USD
Source: Massive (polygon.io)
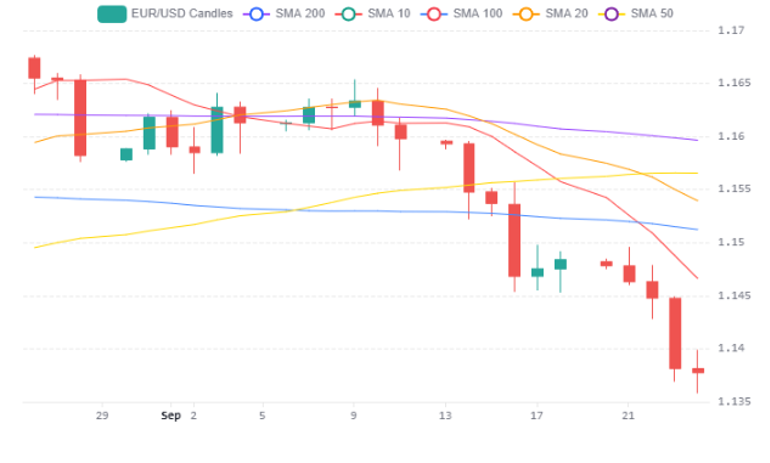
The EUR/USD pair remains under pressure, driven by a powerful combination of hawkish Federal Reserve policy, surging U.S. Treasury yields, and energy-related headwinds for the eurozone. The Fed's hawkish narrative coupled with robust U.S. economic data—including jobless claims at a two-month low and composite PMI jumping to 58.4—has widened the transatlantic interest rate differential decisively in the dollar's favour. The bond market selloff, with 10-year Treasury yields breaching 5.15% and 30-year yields climbing above 5.45%, is creating a powerful gravitational pull toward dollar-denominated assets that the euro cannot currently counteract.
Rising oil prices, with Brent crude above $106 per barrel amid Middle East tensions, disproportionately weigh on the energy-import-dependent eurozone, while the ECB's comparatively passive stance—with only a 54% probability of a 25basis point hike priced in—offers the single currency little fundamental support. Although improving eurozone data, including a German Ifo index at a three-year high of 89.9, provides a glimmer of resilience, these positives have been overwhelmed by dollar-supportive forces.
From a technical perspective, EUR/USD is trading near 1.1376, well below the clustered 200-day, 50-day, and 20-day moving averages in the 1.1550–1.1600 zone, confirming entrenched bearish momentum. The daily RSI near 22 is deeply oversold, raising the possibility of a mean-reversion bounce toward the 1.1500–1.1600 resistance area, though the alignment of all major moving averages overhead acts as a formidable ceiling. A failure to hold the 1.1360 support level would expose the year-to-date trough near 1.1330, and absent a material shift in the macro backdrop, the path of least resistance for EUR/USD remains to the downside.
USD / JPY
Source: Massive (polygon.io)
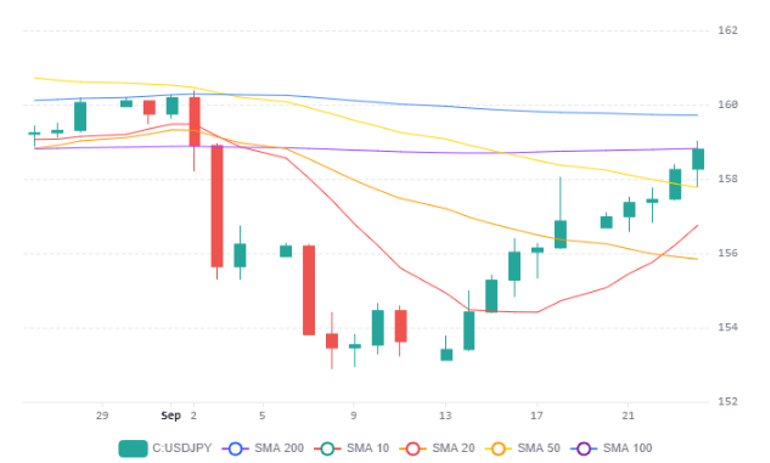
USD/JPY has climbed steadily over the past week, advancing roughly 2.4% from the mid-155 region to trade near 158.80, now testing the critical 200-day moving average around 159. This rally is underpinned by a widening U.S.-Japan interest rate differential, with the 10-year Treasury yield surging above 5.15%—its highest since 2007—while the Fed signals further tightening with market expectations for another rate hike at the October meeting climbing to approximately 70%. Although the Bank of Japan raised its policy rate to 1.25% in September, the highest in 31 years, two dissenting board members and the absence of a larger hike left markets unconvinced that the BOJ can close the rate gap with the Fed quickly enough to support the yen.
Geopolitical risks are compounding yen weakness, as Middle East conflict and disrupted oil supplies hit Japan particularly hard given its dependence on energy imports, threatening to push consumer inflation above 3% and further eroding the currency's purchasing power. Japan's record 15.4 trillion yen intervention last month has proven short-lived, with the pair drifting back toward the psychologically significant 160 level widely regarded as the intervention zone.
From a technical perspective, the pair sits above the 50-day SMA near 158 with the daily RSI pushing above 60 for the first time in over a month, confirming bullish momentum, though the 200-day moving average at approximately 159 represents formidable resistance where institutional activity has been concentrated. A decisive break above this level could open the path toward the 161 resistance cluster, while failure here risks a pullback toward 158 and the 50-day SMA, particularly if Japanese authorities signal renewed willingness to intervene.
GBP / USD
Source: Massive (polygon.io)
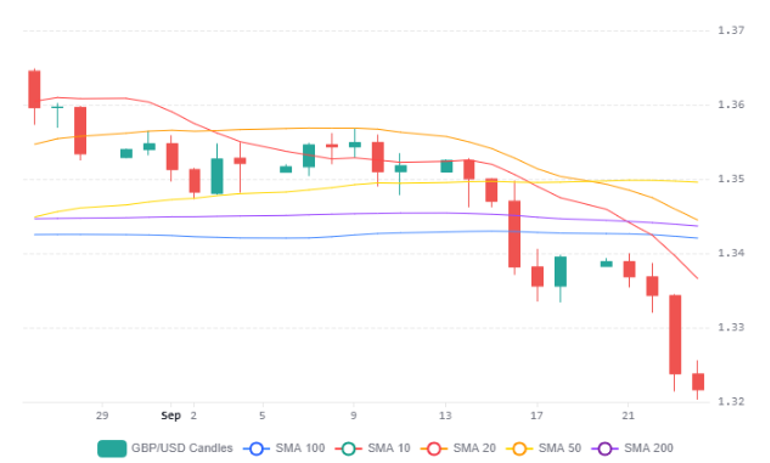
GBP/USD has extended its punishing decline, falling for four consecutive sessions to its lowest level in over a month near 1.3211, driven by a powerful resurgence in the US dollar as surging Treasury yields—with the 10-year climbing above 5.15%—and hawkish Fed rhetoric widen the rate differential against sterling. The pair now trades well beneath all key moving averages, including the 200-day SMA near 1.3400 and the 50-day SMA around 1.3500, while the daily RSI has plunged to approximately 22, reflecting unusually deep oversold conditions relative to the prior 30-day period.
Sterling's vulnerability is compounded by questions over the Bank of England's tightening path; although the BoE held rates at 3.75% with a hawkish tone, markets may be overpricing further hikes, with some analysts expecting only two more increases before an eventual cutting cycle. Weak UK labour demand, cooling business activity, and the prospect of another real income squeeze from elevated energy prices—Brent crude now above $106—present significant headwinds that contrast sharply with remarkably strong US economic data, including jobless claims near 57-year lows and multi-year highs in manufacturing and services PMIs.
From a technical standpoint, the extremely oversold RSI raises the possibility of a mean-reversion bounce back toward the 20-day SMA around 1.3400, but the bearish scenario of continued momentum-driven selling through the 1.3200 handle toward the 2025 low near 1.3015 remains credible. Fundamentally, with the global bond selloff showing no signs of abating and the US-UK growth and rate differential continuing to widen, the path of least resistance for GBP/USD remains firmly to the downside.
Economic Calendar