


EUR / USD
Source: Massive (polygon.io)
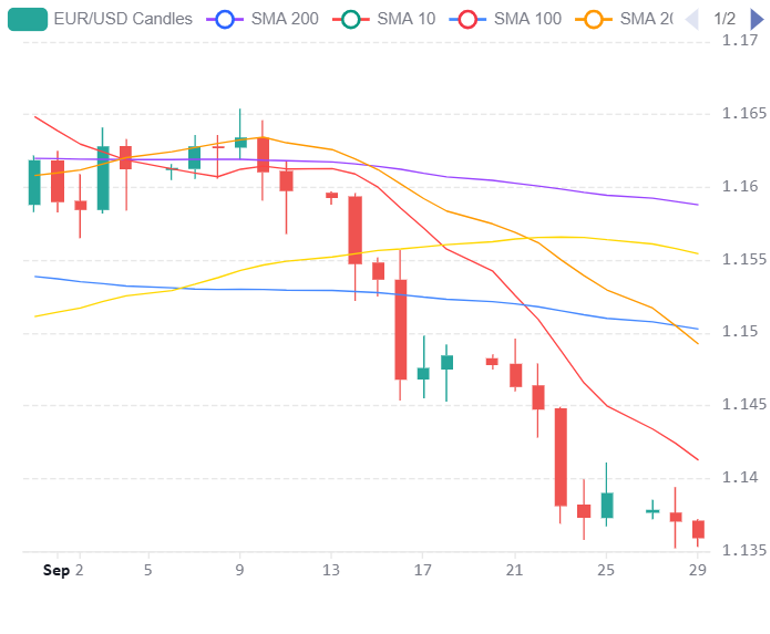
EUR/USD remains under significant downward pressure around 1.1362, having lost almost 2% over the past month as widening policy divergence continues to favour the dollar. US Treasury yields have risen to their highest levels since 2007, while markets now assign around a 70% probability to another Fed rate increase in October, compared with less than 18% a month ago. This contrasts with a more measured ECB outlook, with markets pricing only around a 37% probability of an October increase.
Elevated energy prices are adding to the euro’s difficulties. Brent crude above USD 106 per barrel represents a significant headwind for the energy dependent eurozone economy, while simultaneously reinforcing US inflation concerns and expectations of further Fed tightening. The divergence in economic momentum also remains supportive for the dollar, with US growth expectations considerably stronger than those for the eurozone.
Technically, EUR/USD remains below the 20 day, 50 day and 200 day SMAs, confirming the broader downward trend. The daily RSI around 24 indicates deeply oversold conditions, increasing the possibility of a corrective recovery towards the 20 day SMA near 1.1500. We see the June low around 1.1329 as the critical downside support, with a decisive break potentially extending the decline. We expect this week’s US PCE inflation and nonfarm payrolls data to determine whether the current dollar momentum can persist or whether softer readings provide scope for a near term euro recovery.
USD / JPY
Source: Massive (polygon.io)
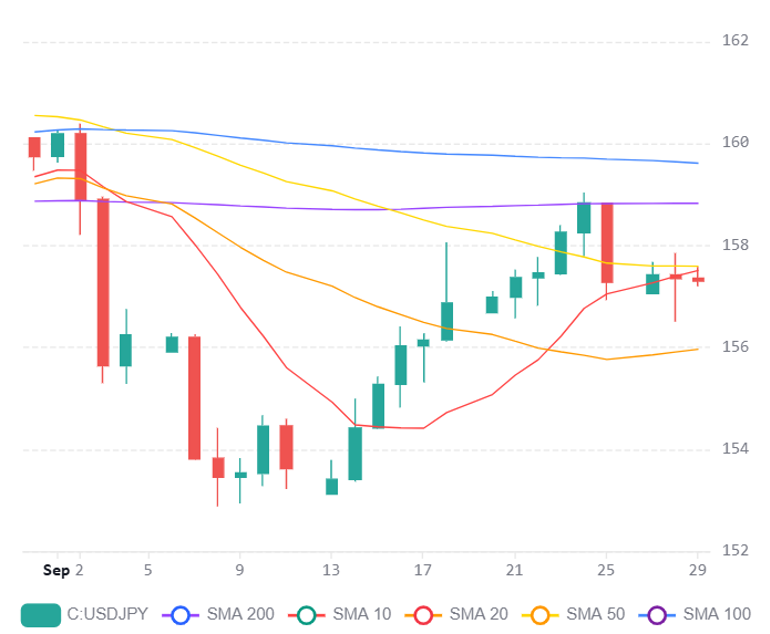
USD/JPY is trading around 157.28 as the pair remains caught between the dollar’s substantial yield advantage and increasing pressure for a stronger yen. The BoJ’s increase to 1.25%, alongside stronger services inflation and discussion of further tightening, is gradually narrowing the policy differential. However, elevated US yields and Brent crude above USD 106 per barrel continue to support the dollar while worsening Japan’s energy import burden.
Technically, USD/JPY remains below the 50 day SMA near 158 and the 200 day SMA around 159, maintaining the broader weaker structure. At the same time, price is holding above the 20 day SMA near 156 and close to the 30 day VWAP around 157. The daily RSI around 51 reflects broadly neutral momentum, consistent with the recent two way price action around the 157 area.
We see the 158 to 159 region as the key resistance zone required to establish a more convincing recovery, with a sustained break above the 50 day SMA strengthening the case for further upside. Conversely, failure to hold 156.50 would weaken the near term structure and could expose 156 followed by the deeper support region around 153. We expect intervention concerns and expectations of further BoJ tightening to limit the extent of dollar upside, even while the underlying rate differential remains supportive for USD/JPY.
GBP / USD
Source: Massive (polygon.io)
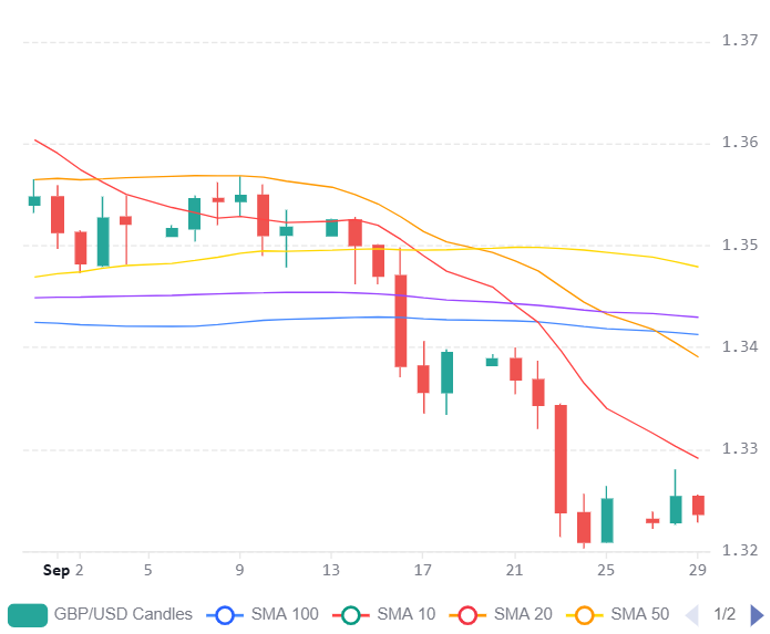
GBP/USD remains under sustained pressure around 1.3239, with the pair trading well below the 20 day and 200 day SMAs and the 30 day VWAP clustered around 1.3400. The fundamental backdrop continues to favour the dollar, with markets assigning around a 70% to 73% probability to another Fed increase in October. The BoE, meanwhile, faces a more difficult policy environment as elevated inflation pressures collide with signs of weakening employment and wage growth.
Brent crude above USD 105 per barrel adds to the challenge by intensifying inflationary pressure while threatening UK growth. Rising unemployment, declining payrolls and moderating private sector wage growth leave the economy more vulnerable to additional tightening. We see this combination of weaker domestic activity and persistent inflation as an important constraint on sterling, particularly while US economic growth and Treasury yields remain comparatively strong.
Technically, the daily RSI around 31 indicates increasingly oversold conditions, although repeated failures around 1.3268 suggest sellers remain in control. We see 1.3209 as the immediate support, with a sustained break potentially opening the way towards the June low around 1.3147. We expect oversold conditions to provide scope for a corrective recovery if upcoming US PCE inflation or payrolls data disappoint, although GBP/USD would need to reclaim the 1.3400 moving average cluster before the broader technical outlook begins to improve.


