


EUR / USD
Source: Massive (polygon.io)
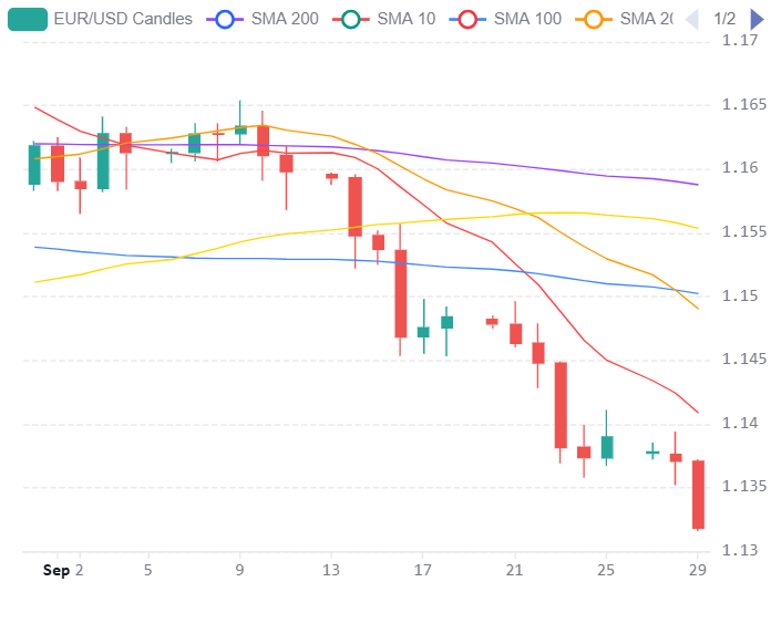
EUR/USD remains under intense selling pressure around 1.1315, its weakest level in more than a year, as widening rate differentials and surging US Treasury yields continue to favour the dollar. The US 10 year yield has climbed above 5.25%, reflecting persistent inflation concerns, resilient economic activity and expectations of further Fed tightening. Markets now assign more than a 70% probability to another rate increase in October, contrasting with a considerably more cautious ECB outlook as eurozone growth weakens.
Technically, the decline has become increasingly stretched. The daily RSI has fallen towards 20, placing the pair firmly in oversold territory, while price remains well below the 20 day, 50 day and 200 day SMAs concentrated around 1.1500 to 1.1600. We see scope for these extreme conditions to generate a corrective recovery towards 1.1350 to 1.1400, although the broader technical structure remains firmly negative. Any stronger recovery would encounter significant resistance around 1.1500.
The fundamental backdrop continues to favour the dollar. Brent crude above USD 106 per barrel represents a particularly significant headwind for the energy dependent eurozone, simultaneously threatening growth and sustaining inflationary pressure. We expect the combination of elevated US yields, divergent policy expectations and geopolitical uncertainty to maintain downside pressure on EUR/USD. A sustained break below the current area would leave the pair vulnerable to further losses, while a recovery above 1.1500 would be required to materially improve the broader outlook.
USD / JPY
Source: Massive (polygon.io)
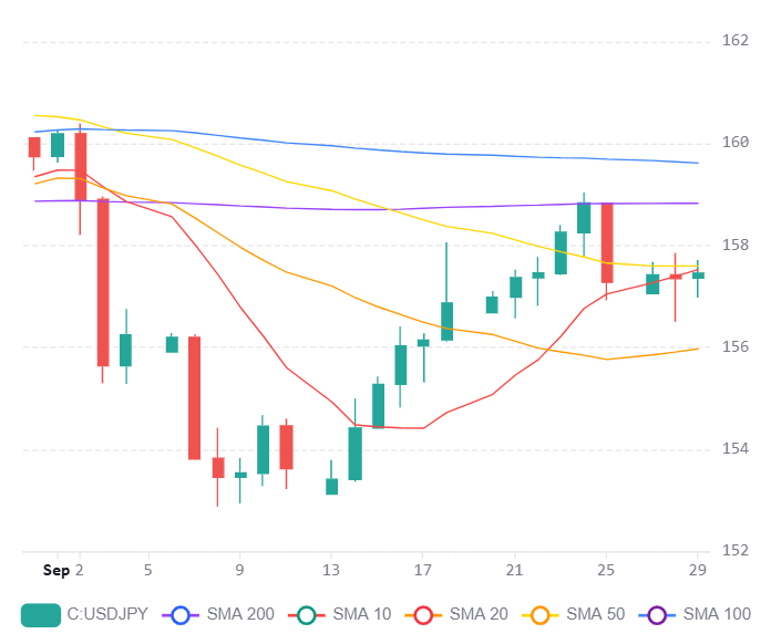
USD/JPY remains caught between elevated US yields and increasingly restrictive Japanese monetary policy, with the pair consolidating around 157.47. The BoJ has raised its policy rate to 1.25%, but expectations of another Fed increase in October continue to preserve a sizeable US Japan rate differential. At the same time, heightened intervention rhetoric and the prospect of further Japanese policy normalisation are limiting the extent to which higher US yields translate into renewed USD/JPY upside.
Technically, the pair remains below the 50 day SMA around 158 and the 200 day SMA near 159, creating an important resistance zone above current levels. The 30 day VWAP around 156.77 and the 20 day SMA near 156 provide support, while the daily RSI around 53 reflects broadly neutral momentum. We see the resulting 156 to 159 range as increasingly important for determining the next directional move.
A sustained break above 159 would improve the technical structure and could shift attention towards 160.60, particularly if upcoming US data reinforce expectations of further Fed tightening. Conversely, a move below 156.77 would weaken the near term picture and could expose deeper support towards 153. We expect intervention concerns and further BoJ tightening expectations to continue limiting upside, leaving USD/JPY particularly sensitive to this week’s US PCE inflation and nonfarm payrolls releases.
GBP / USD
Source: Massive (polygon.io)
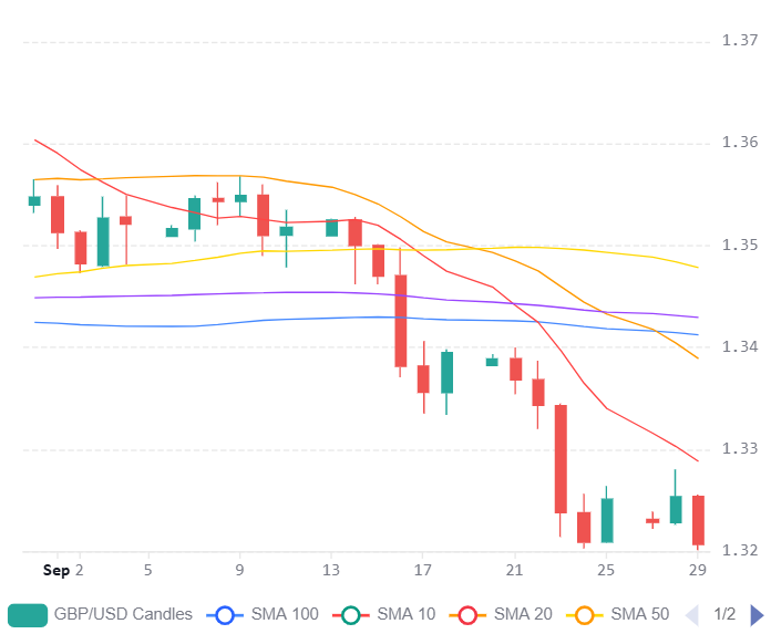
GBP/USD remains under sustained pressure around 1.3202 as rising US Treasury yields and increasingly hawkish Fed expectations strengthen the dollar’s relative appeal. Markets are assigning around a 70% probability to another Fed rate increase in October, while the US 10 year yield above 5.25% has widened the yield advantage of dollar denominated assets. The BoE outlook is less clear, with policymakers divided over whether elevated inflation warrants additional tightening as domestic economic conditions weaken.
Technically, GBP/USD has fallen below the 20 day, 50 day and 200 day SMAs, reinforcing the broader downward structure. The daily RSI around 29 indicates deeply oversold conditions, however, suggesting the recent decline is becoming increasingly stretched. We see scope for a corrective recovery towards the 1.3400 area if dollar momentum begins to moderate, although this former support region should now provide significant resistance.
We expect the June low around 1.3147 to become increasingly important if sellers retain control. A decisive break below this level would reinforce the bearish structure and leave the pair vulnerable to a deeper decline. Conversely, softer US inflation or employment data could encourage some unwinding of Fed tightening expectations and provide sterling with room for a relief recovery. For now, elevated US yields, geopolitical uncertainty and the comparatively cautious BoE outlook continue to favour the dollar.


