


EUR / USD
Source: Massive (polygon.io)
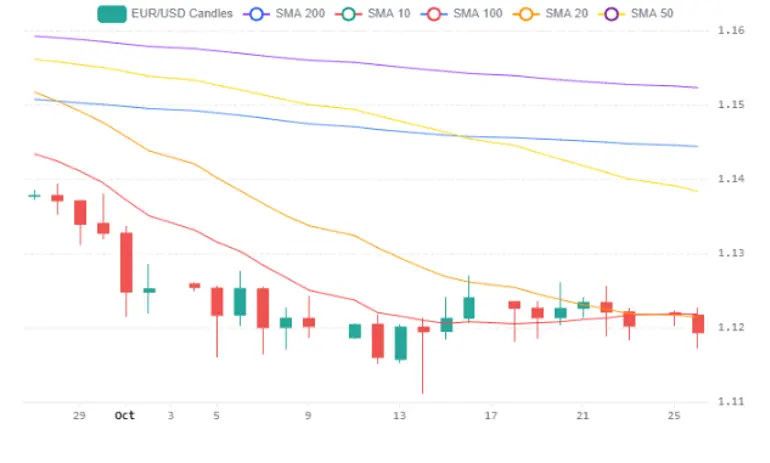
EUR/USD remains under pressure around 1.1200 as markets prepare for this week’s Fed and ECB policy decisions. Both central banks are expected to leave rates unchanged, maintaining a substantial interest rate differential in favour of the dollar. The European backdrop remains challenging, with elevated French sovereign yields and widening fiscal concerns weighing on confidence in the single currency. Meanwhile, geopolitical uncertainty and Brent crude above USD 110 per barrel continue to support safe haven demand for the dollar while increasing economic pressures across the energy dependent eurozone.
Germany’s Ifo business climate index offered a modestly encouraging signal at 90.2, with stronger expectations suggesting some improvement in business sentiment. However, we see this as insufficient to offset broader eurozone weaknesses, particularly while French fiscal uncertainty and elevated energy costs continue to constrain growth. Attention now turns to the Fed’s guidance and upcoming US GDP and core PCE inflation data, which should provide further clarity on the likelihood of additional tightening in December and the outlook for the transatlantic rate differential.
Technically, EUR/USD remains below the 50 day SMA around 1.1400, the 200 day SMA near 1.1500 and the 30 day VWAP around 1.1300, maintaining the broader bearish structure. The daily RSI near 36 has turned lower again, indicating that the recent recovery in momentum is losing strength. We see a sustained move above the 20 day SMA near 1.1200 as necessary to support a corrective recovery towards 1.1280. Conversely, failure to stabilise around current levels would maintain pressure on the October low near 1.1116, with a decisive break potentially exposing 1.1050 to 1.1000.
USD / JPY
Source: Massive (polygon.io)
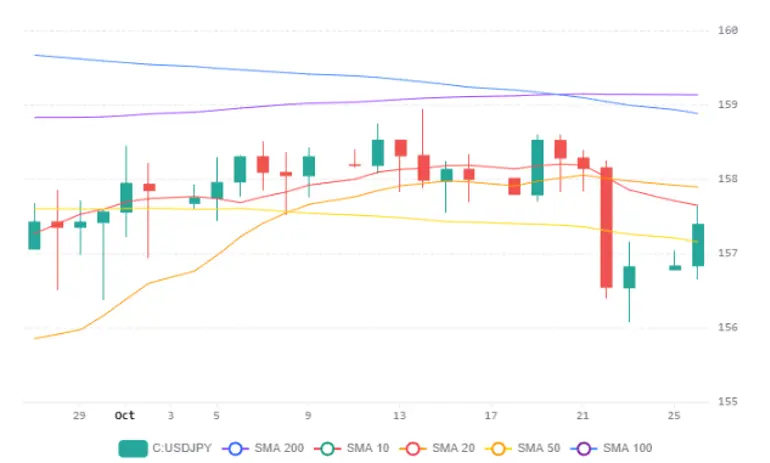
USD/JPY has recovered from its recent low near 156.39 to around the 50 day SMA at 157.15, although gains have stalled beneath the 20 day SMA and 30 day VWAP clustered around 157.90. The pair remains caught between the substantial US Japan interest rate differential and growing expectations of further BoJ tightening. The Fed is widely expected to maintain rates at 3.75% to 4.00%, while resilient US growth and persistent inflation continue to support elevated Treasury yields and the dollar’s relative appeal.
The Japanese policy outlook is becoming increasingly supportive of the yen, with the BoJ expected to signal greater confidence in achieving its inflation target and potentially revise its longer term inflation projections higher. Markets are assigning around a 77% probability to a December rate increase, reflecting expectations of continued policy normalisation. We see this gradual narrowing of monetary policy divergence, alongside persistent intervention concerns, as an important constraint on sustained USD/JPY upside. However, hawkish Fed guidance could temporarily reinforce the dollar’s yield advantage and limit the scope for yen appreciation.
Technically, USD/JPY remains below the 20 day SMA and 30 day VWAP around 157.87 to 157.90, while the 200 day SMA near 159.14 provides further resistance. The daily RSI around 48 reflects broadly neutral momentum, suggesting that the recent recovery has yet to establish a convincing upward trend. We expect a sustained break above 157.90 to improve the technical outlook and potentially open the way towards 159. Conversely, rejection from this resistance region could return attention towards 156.65, with a deeper decline exposing the broader support area around 153. The upcoming Fed and BoJ decisions should be particularly important in determining whether the recent improvement in yen sentiment can continue.
GBP / USD
Source: Massive (polygon.io)
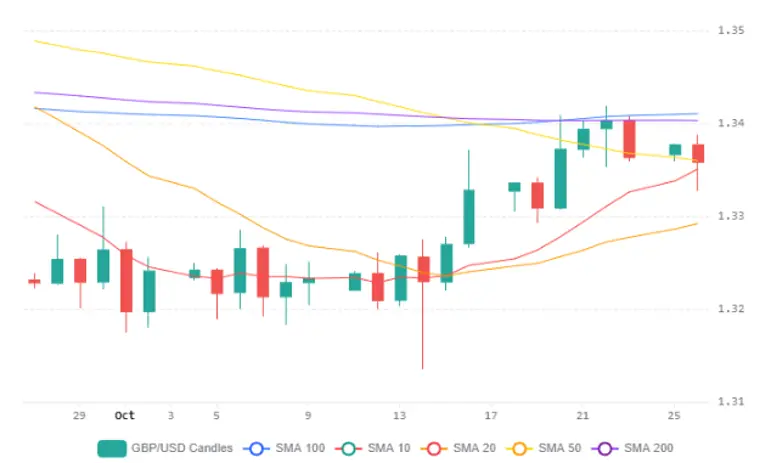
GBP/USD has edged lower to around 1.3356 after briefly testing 1.3327, as weaker UK economic data and uncertainty ahead of Wednesday’s Autumn Budget weigh on sterling. September retail sales volumes declined by 0.4%, exceeding expectations of a modest contraction, while consumer confidence recorded its sharpest monthly deterioration since the pandemic. These developments have raised concerns over domestic demand and complicated expectations of further BoE tightening, particularly as markets assess the potential growth implications of upcoming fiscal measures.
The UK Budget represents a significant near term catalyst, with investors anticipating measures to rebuild fiscal headroom and reduce longer dated gilt issuance. However, any deviation from these expectations could increase volatility in gilt markets and place additional pressure on sterling. Meanwhile, the Fed is widely expected to leave rates unchanged, although persistent US inflation and elevated energy costs continue to support expectations of another increase in December. We see this combination of UK fiscal uncertainty and comparatively resilient US economic conditions as limiting the pound’s recovery potential.
Technically, GBP/USD remains below the 50 day and 200 day SMAs clustered around 1.3400, while the daily RSI near 54 indicates moderately positive momentum despite the recent retreat. We see 1.3400 as the critical resistance level, with a sustained break potentially strengthening the recovery towards 1.3500. Conversely, failure to overcome this region would leave the pair vulnerable to renewed selling, with a break below 1.3327 potentially exposing the mid October support around 1.3150. We expect the UK Budget and Fed policy guidance to determine the next directional move, with near term risks remaining tilted modestly to the downside.

