


EUR / USD
Source: Massive (polygon.io)
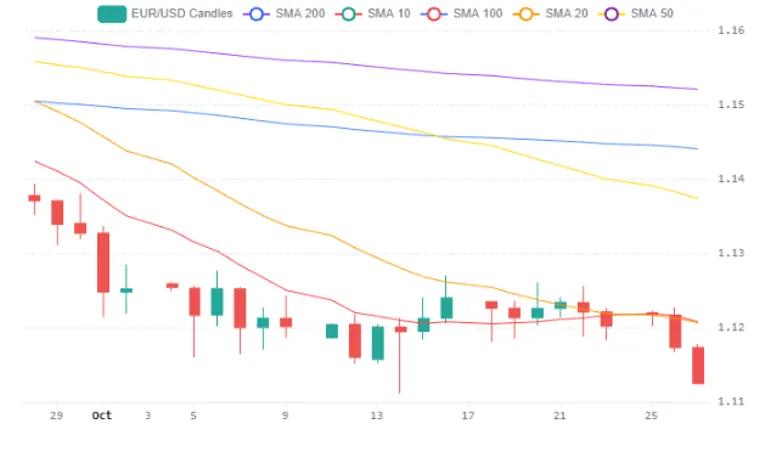
EUR/USD remains under sustained pressure around 1.1125, having declined approximately 3.6% over the past month as European fiscal concerns, elevated energy costs and widening policy divergence continue to favour the dollar. France’s deteriorating fiscal outlook has pushed the French and German sovereign yield spread towards 167 basis points, while weakening credit demand and persistent energy pressures add to the eurozone’s economic challenges. Meanwhile, markets assign around a 70% to 75% probability to another Fed rate increase in December, contrasting with expectations that the ECB will maintain its deposit rate at 2.50% this week.
The fundamental backdrop remains challenging for the euro, with the ECB facing a difficult balance between elevated inflation and deteriorating growth prospects. Attention now turns to President Lagarde’s guidance and upcoming US PCE inflation data, with headline inflation expected around 3.7% year on year. We see the combination of European fiscal fragility and relatively hawkish Fed expectations as maintaining pressure on EUR/USD, although any moderation in US inflation or a more cautious Fed outlook could provide some relief.
Technically, EUR/USD remains well below the 20 day SMA around 1.1200, the 50 day SMA near 1.1400 and the 200 day SMA around 1.1500, confirming the broader bearish structure. The daily RSI around 29 indicates deeply oversold conditions, increasing the possibility of a corrective recovery. We see the October low near 1.1116 as the immediate support level, with a decisive break potentially exposing 1.1050. Conversely, a recovery towards the 20 day SMA around 1.1200 remains possible, although we expect upside to remain limited while the pair trades below its major moving averages.
USD / JPY
Source: Massive (polygon.io)
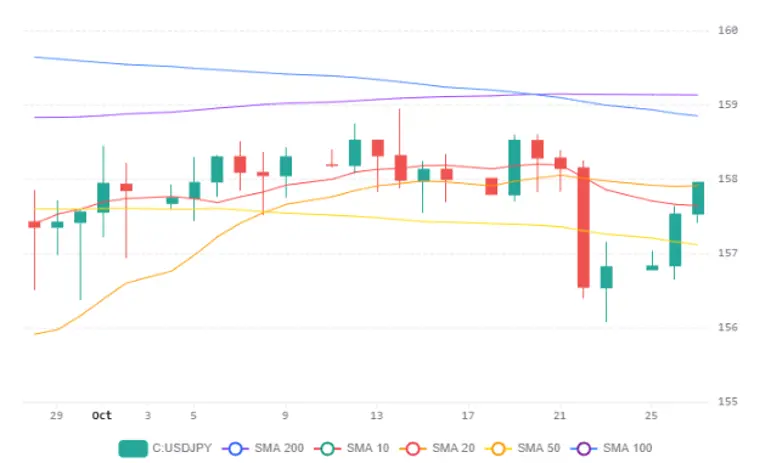
USD/JPY has edged higher towards 158.00 as markets prepare for the Fed and BoJ policy decisions, with the substantial US Japan interest rate differential continuing to support the dollar. The Fed is expected to maintain rates at 3.75% to 4.00%, although persistent inflation and elevated energy costs have reinforced expectations of another increase in December. We see Fed Chair Warsh’s guidance as particularly important, with a hawkish tone potentially extending the recovery while a more cautious outlook could encourage a reversal in recent dollar gains.
The Japanese monetary policy backdrop is becoming increasingly supportive of the yen. The BoJ is expected to maintain its gradual tightening approach, with persistent inflation strengthening the case for further increases towards 1.50% over the coming months. Meanwhile, Japanese investors’ reduction in overseas bond holdings suggests a gradual shift towards domestic assets, potentially providing additional yen support. However, Brent crude near USD 114 per barrel continues to weigh on Japan’s energy import costs, while elevated US yields preserve a substantial advantage for the dollar. We expect these competing forces to limit sustained directional momentum until markets receive greater clarity from both central banks.
Technically, USD/JPY is testing the 20 day SMA and 30 day VWAP around 158.00, while the 200 day SMA near 159.00 remains significant overhead resistance. The daily RSI around 53 reflects broadly neutral momentum, suggesting that the recent recovery has yet to establish a convincing upward trend. We see a sustained break above 158.00 as opening the way towards 159.00, followed by the psychologically important 160.00 level. Conversely, rejection from current levels could return attention towards support around 157.00. For now, we expect USD/JPY to remain sensitive to central bank guidance, with intervention concerns likely to constrain further upside.
GBP / USD
Source: Massive (polygon.io)
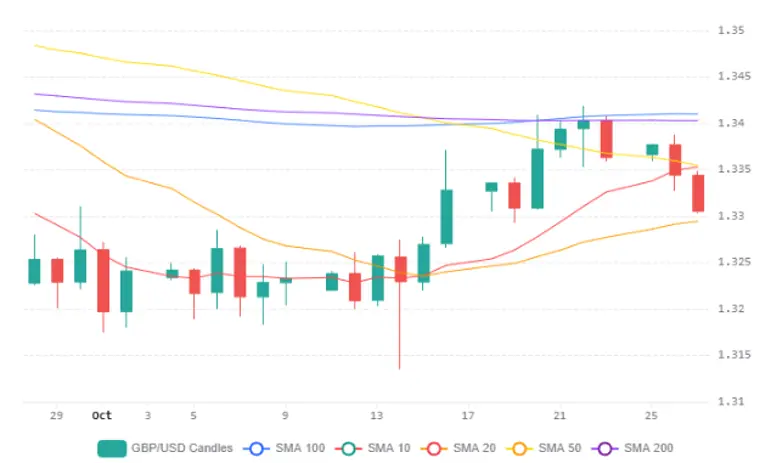
GBP/USD remains under pressure around 1.3305 as improving US economic data and expectations of further Fed tightening continue to support the dollar. Stronger durable goods orders and a recovery in consumer confidence have reinforced the relative resilience of the US economy, while markets assign around a 70% to 75% probability to another Fed rate increase in December. The upcoming Fed decision therefore represents an important catalyst, although the accompanying guidance is likely to have a greater influence on the dollar than the widely expected decision to leave rates unchanged.
Sterling also faces significant domestic uncertainty ahead of Wednesday’s Autumn Budget. With UK borrowing costs already elevated, any fiscal measures that increase expected government borrowing could place additional pressure on gilt yields and investor confidence. Although the pound has demonstrated relative strength against the euro, this has provided limited support against the dollar. We see the combination of UK fiscal uncertainty and relatively hawkish Fed expectations as maintaining a cautious outlook for GBP/USD, particularly if the Budget fails to reassure investors over fiscal sustainability.
Technically, GBP/USD remains below the 50 day and 200 day SMAs clustered around 1.3400, while the daily RSI near 48 reflects broadly neutral momentum. We see 1.3300, which coincides with the 30 day VWAP, as the immediate support level required to prevent further weakness. A sustained break below this area could expose the mid October low around 1.3150, while a recovery above 1.3400 would be required to improve the broader technical structure. We expect the Fed decision and UK Budget to determine the next directional move, with near term risks remaining tilted modestly to the downside.

