EUR / USD
Source: Massive (polygon.io)
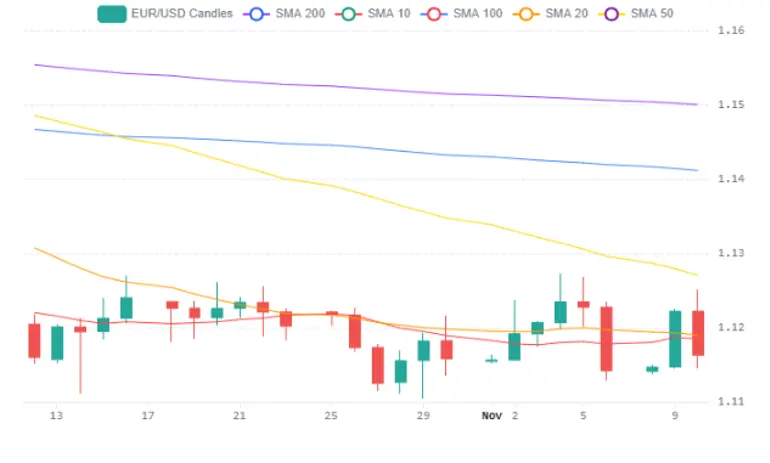
EUR/USD came under heavy pressure today after hotter-than-expected US October inflation, with headline prices up 0.4% month over month and core up 0.3% for a third straight month. A December Fed hike is now fully priced, with roughly 15% odds of a half-point move, as US two-year yields jumped as much as 20 basis points against only about 6 basis points for German two-year yields.
After peaking near 1.125 in the European morning, the pair sold off sharply on the day's heaviest volume to about 1.1146, a decline of roughly 0.5%, before steadying around 1.116 in what looks more like exhaustion than fresh demand. Spot sits below the 20-day average of 1.12, with the falling 50-day (about 1.1327) and 200-day (about 1.1535) overhead, while a daily RSI near 44 signals bearish momentum that is not yet stretched.
The euro retains some support from October euro zone inflation of 4% and a roughly 75% priced chance of a December ECB hike. However, steady core inflation of 2.5% points to energy-driven pressure, leaving the ECB less compelled to tighten than the Fed. Weak 2027 growth prospects, tighter fiscal policy and political risk ahead of April's French elections add further headwinds, although falling oil prices on US-Iran de-escalation offer a partial offset.
Technically, holding the late-October floor near 1.1115 and reclaiming 1.12 could open a squeeze toward 1.129. On balance, the dollar should stay resilient in the coming months, with a meaningful euro recovery more likely next spring as US energy base effects fade and Fed expectations soften.
USD / JPY
Source: Massive (polygon.io)
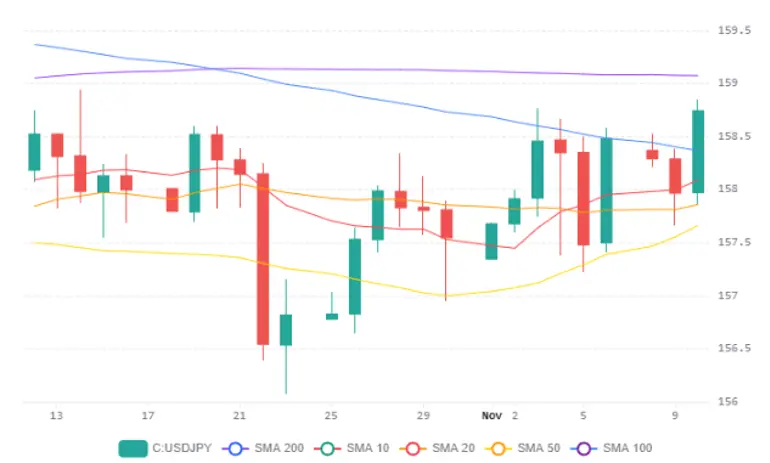
USD/JPY rose about 0.5% over the past day to around 158.73, breaking higher in the early US session on the day's heaviest volume and peaking near 158.85. The pair now trades above its 50-day SMA (157.26) and 20-day SMA (157.96), with daily RSI near 57. It is pressing against two key barriers: the October high at 158.94 and the 200-day SMA at 158.69.
Fundamentals favour the dollar. October CPI rose 0.4% month-over-month and core rose 0.3%, both a tenth above forecasts, and with 165,000 jobs added in October and unemployment at 4.1%, markets price roughly a 90% chance of a December Fed hike. In Japan, September household spending fell 6.8% year-over-year, its steepest drop since 2020. That weakness has blunted support for the yen even though the Bank of Japan's hawkish October summary of opinions signals a likely December hike from 1.25%.
A daily close above 159.10 would open a path toward 160 and potentially 161, while rejection near 159 would point to a retest of the 157.70–158 cluster, with support at 156.50 below. We expect USD/JPY to remain range-bound in the near term, particularly as the US holiday is likely to keep liquidity thin during today’s session.
GBP / USD
Source: Massive (polygon.io)
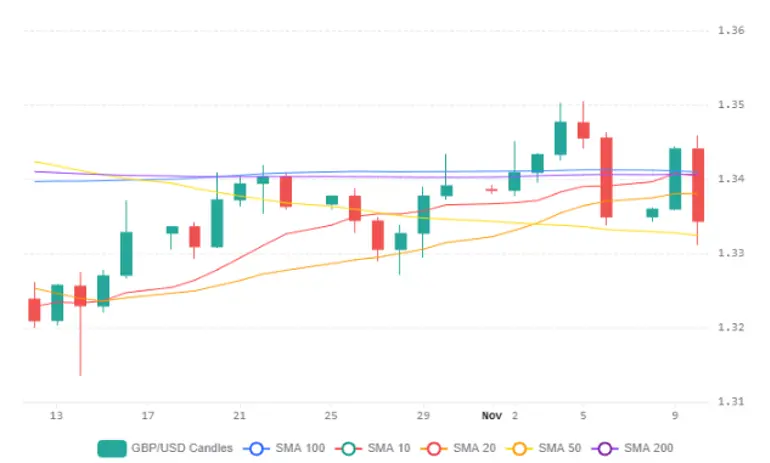
GBP/USD fell about 0.7% to settle near 1.334 after sellers decisively rejected resistance at 1.346, with the slide bottoming near 1.331 on an unusually wide 1.1% intraday range. The main driver was a hawkish repricing of Federal Reserve policy after October US consumer prices rose 0.4% on the month against a 0.3% forecast. Markets now treat a December hike as near certain and assign meaningful odds to a 50 basis point move.
The Bank of England raised Bank Rate to 4.00% last week and has signalled that another near-term increase is likely, but a narrowing gilt-Treasury yield gap shows that relative rate momentum favours the dollar. Earlier sterling strength rested more on dollar weakness than on UK fundamentals, which makes Thursday's third-quarter GDP release a key test.
Technically, the pair has broken below the 200-day and 20-day moving averages near 1.34, and the daily RSI has eased to about 48, leaving 1.33 as pivotal support. A sustained break below 1.33 would expose 1.328 and possibly the mid-October trough around 1.315. The near-term bias stays defensive for sterling, though lower oil prices and a post-midterm political shift could temper Fed hawkishness and soften the dollar from next spring.
Economic Calendar